Retirement Planning Insights
Practical retirement planning guides to help you build, protect and draw down a retirement corpus with confidence.
20 articles
All Insights
Money n Wealth · Insights
Is ₹1 Crore Enough to Retire in India? Finding Your Magic Number
2026 · Retirement Planning
Is ₹1 Crore Enough to Retire in India? Finding Your Magic Number (2026)
At 6% inflation, ₹1 crore in 25 years buys what ₹23 lakh buys today. Here is how to work out your own retirement magic number, with corpus tables, a worked example and a seven-step checklist.
Money n Wealth · Insights
Retirement Planning at 40
2026 · Retirement Planning
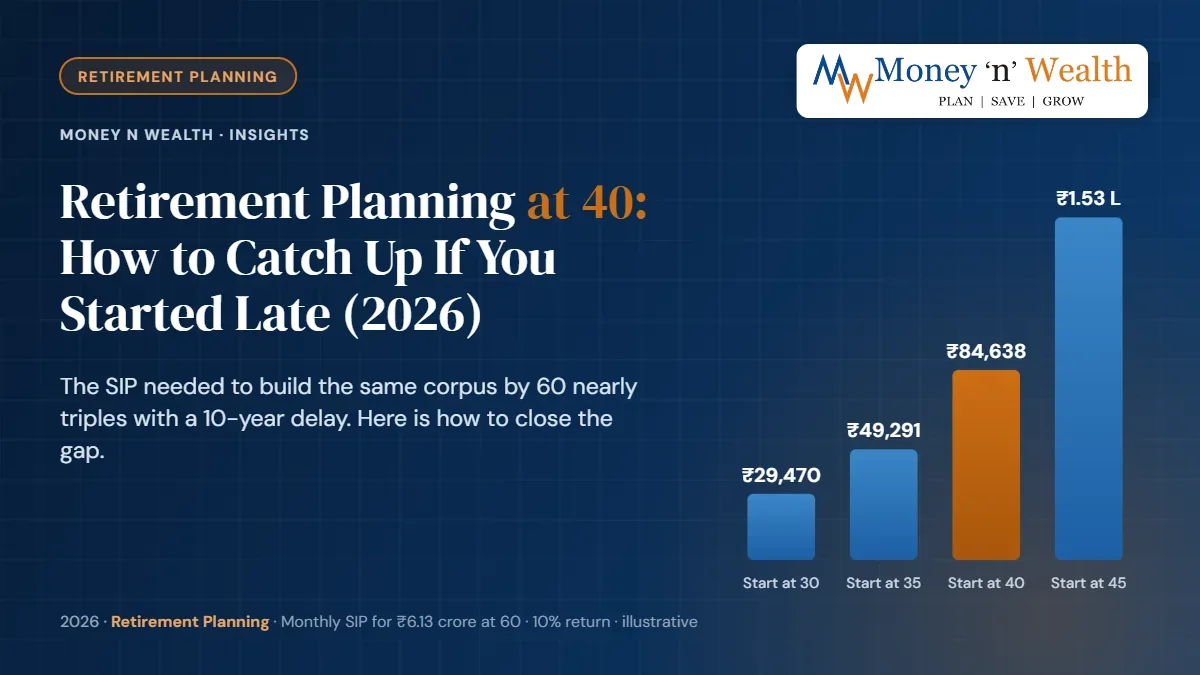
Retirement Planning at 40: How to Catch Up If You Started Late (2026)
Building the same retirement corpus by 60 needs a SIP almost three times larger if you start at 40 instead of 30. But EPF, a yearly step-up and working two extra years can cut a 40-year-old's required SIP by more than two-thirds. Here is the catch-up maths.
Money n Wealth · Insights
Is ₹2 Crore Enough to Retire in India? Monthly Income and How Long It Lasts
2026 · Retirement Planning
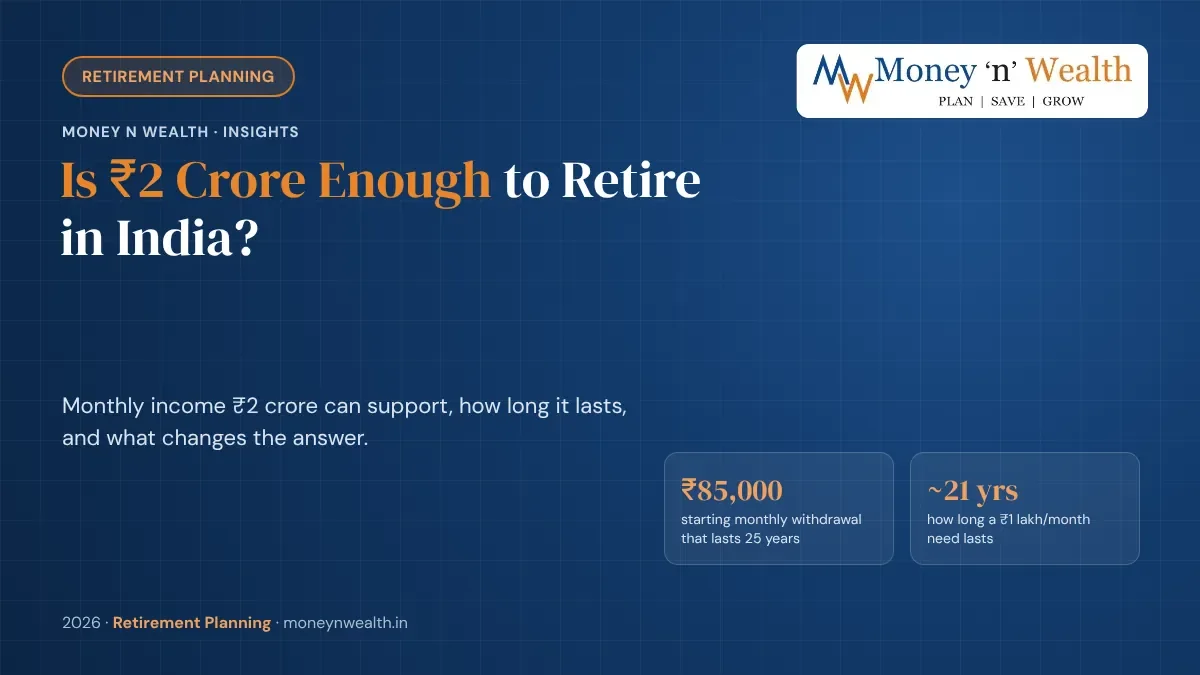
Is ₹2 Crore Enough to Retire in India? Monthly Income and How Long It Lasts
How much monthly income ₹2 crore can support, how long it lasts at ₹50,000 to ₹1.25 lakh a month, and what changes the answer, with clear assumptions and tables.
Money n Wealth · Insights
How Much Monthly Income Can ₹10, 15, 20 or 25 Lakh Give in Retirement?
2026 · Retirement Planning
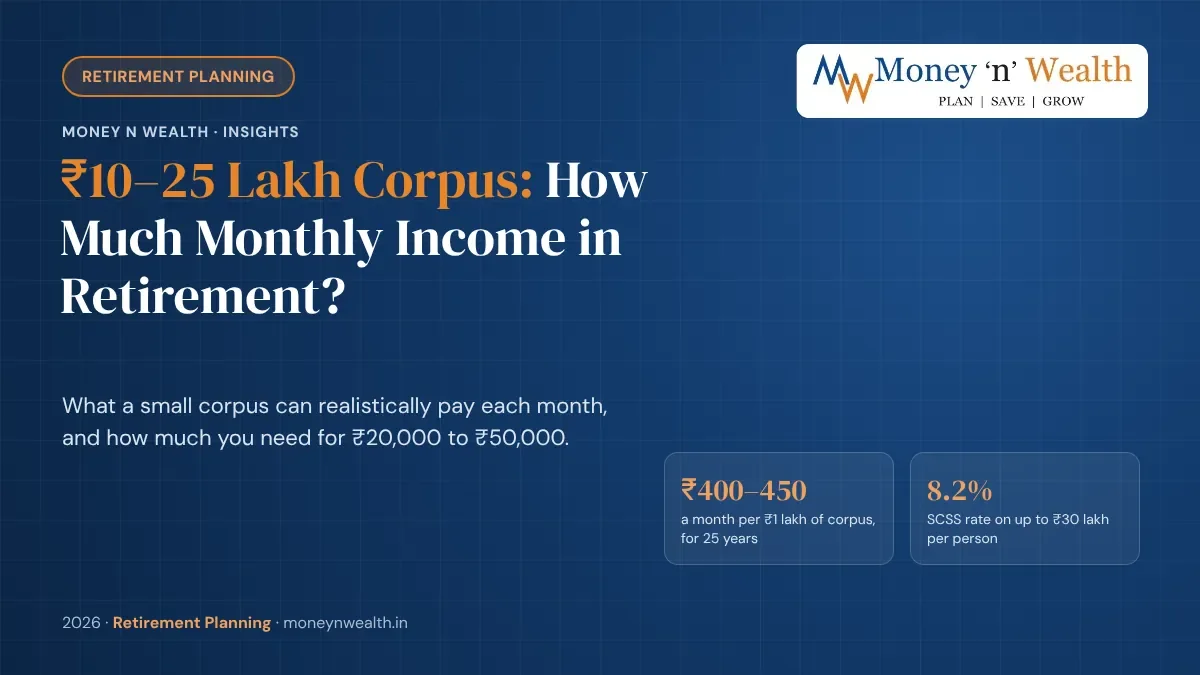
How Much Monthly Income Can ₹10, 15, 20 or 25 Lakh Give in Retirement?
What a small retirement corpus can realistically pay each month, whether ₹16 lakh can sustain ₹30,000 a month, and how much corpus ₹20,000 to ₹50,000 a month needs.
Money n Wealth · Insights
Gratuity Calculation 2026
2026 · Retirement Planning
Gratuity Calculation 2026: Formula, Eligibility and ₹20 Lakh Tax-Free Limit
Ten years on a ₹1 lakh basic earns you about ₹5.77 lakh of gratuity, and the new labour codes can push that higher by widening what counts as wages. Here is the 15/26 formula, who now qualifies after one year, and how the ₹20 lakh tax-free limit works.
Money n Wealth · Insights
Your FIRE Number
2026 · Retirement Planning
Your FIRE Number: How Much You Need to Retire Early in India (2026)
A Pune couple spending ₹1 lakh a month today needs about ₹6.45 crore to retire at 45, not the ₹3 crore a quick 25x rule suggests. Here is how to calculate your FIRE number for Indian inflation, a 50-year retirement and rising health costs.
Money n Wealth · Insights
Five Years to Retirement
2026 · Retirement Planning
Five Years to Retirement: The Pre-Retirement Checklist for 2026
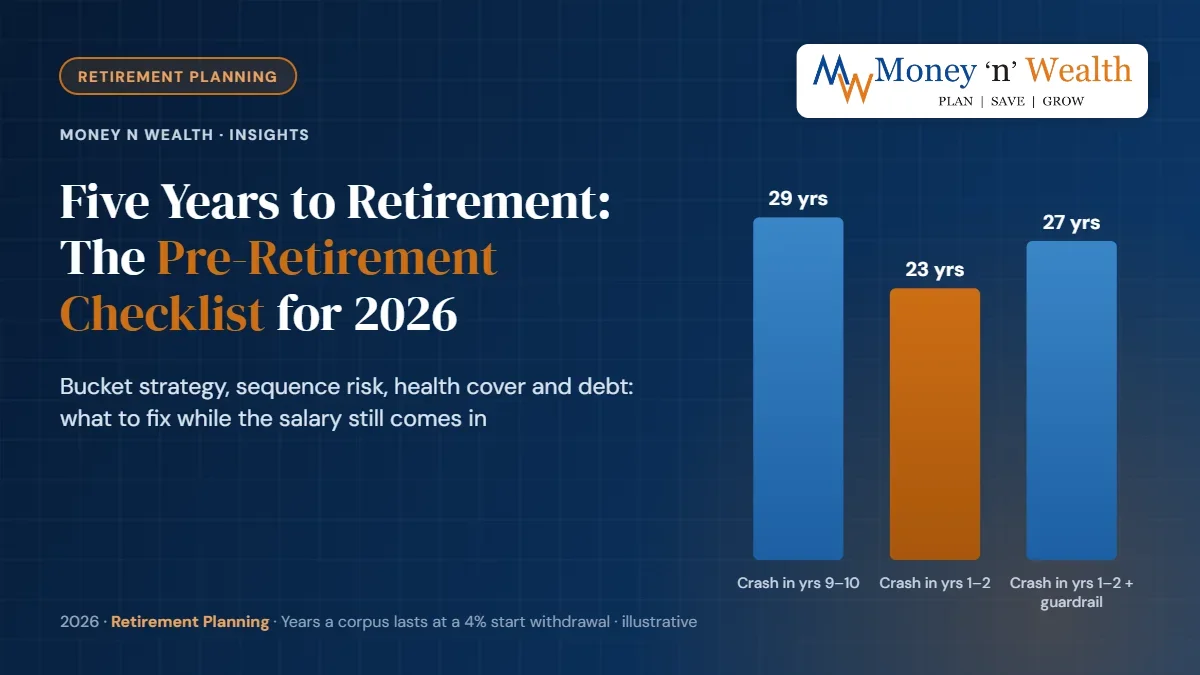
In our example, a market crash in the first two years of retirement makes a ₹3.33 crore corpus run out five years sooner than the same crash ten years later. The five years before you retire are when you defuse that risk. Here is the year-by-year pre-retirement checklist.
Money n Wealth · Insights
EPF/VPF Rules 2026
2026 · Retirement Planning
EPF/VPF Rules 2026: New Withdrawal Limits, Tax and Transfers Explained
Under the EPF Scheme, 2026 you can make partial withdrawals after just 12 months of membership, but 25% of your balance now stays locked and full settlement after leaving a job needs 12 months of unemployment. Here is what changed, how VPF is taxed and how to move PF on a job switch.
Money n Wealth · Insights
EPF Calculator 2026
2026 · Retirement Planning
EPF Calculator 2026: How Your PF and EPS Pension Grow (₹25,000 Ceiling)
A 30-year-old on ₹50,000 basic can retire with roughly ₹2.8 crore in EPF at today's 8.25% rate, but only if both sides contribute on full basic. Here is how the 12% + 12% split, the new ₹25,000 wage ceiling and the EPS pension formula actually work.
Money n Wealth · Insights
Retirement Income for 25 Years
2026 · Retirement Planning
Retirement Income for 25 Years: Pension, Rent or SWP?
A plan that works at 65 must still work at 85. See how pensions, rental income and mutual fund SWPs behave over 25 years, and how to combine them so essentials never depend on markets or tenants.
Money n Wealth · Insights
NPS Payout Choices
2026 · Retirement Planning
NPS Payout Choices: RIS vs Annuity vs Systematic Withdrawal
An annuity is an insurance contract; a systematic withdrawal or RIS keeps your money invested. Here is how the three NPS payout routes differ, and what PFRDA's May 2026 circular added.
Money n Wealth · Insights
NPS Annuity Options Explained
2026 · Retirement Planning
NPS Annuity Options Explained: 5 Payout Choices for Retirement
The annuity you pick at NPS exit decides who keeps getting paid and for how long. Here is how the five common structures trade starting pension against spouse income and legacy.
Money n Wealth · Insights
NPS Changes 2026
2026 · Retirement Planning
NPS Changes 2026: Seven Updates Every Indian Investor Should Understand
NPS now allows a bigger lump sum, a ₹8 lakh full-withdrawal limit, higher-equity schemes and new payout schemes. Here is what changed, what it means and what to check before acting.
Money n Wealth · Insights
NPS Tier 1 vs Tier 2
2026 · Retirement Planning
NPS Tier 1 vs Tier 2: Tax, Liquidity and Retirement Roles Explained
Tier I and Tier II sit on the same NPS platform but do very different jobs. Compare tax benefits, withdrawal limits and liquidity before deciding where each rupee goes.
Money n Wealth · Insights
NPS After 60
2026 · Retirement Planning
NPS After 60: Should You Withdraw, Defer or Keep the Account Running?
Turning 60 with an NPS account no longer means one big withdrawal plus a forced annuity. Here is how exit, deferral, staged payouts and continuation compare under the rules in force in 2026.
Money n Wealth · Insights
Retirement Planning for Couples in India
2026 · Retirement Planning
Retirement Planning for Couples in India: One Household, Two Lifetimes, One Coordinated Plan
Two retirement plans added together do not make one couple's plan. Learn how to coordinate ages, assets, survivor income, NPS annuity choices, health cover and nominations so either spouse can manage alone.
Money n Wealth · Insights
Retirement Income Strategy in India
2026 · Retirement Planning
Retirement Income Strategy in India: How to Turn Your Corpus Into a Monthly Paycheque
Building the corpus is half the job; turning it into a reliable monthly paycheque for 30 years is the other half. Here is a bucket-based plan with a ₹2 crore example and current 2026 rates.
Money n Wealth · Insights
Retirement Planner in Pune
2026 · Retirement Planning
Retirement Planner in Pune: A Step-by-Step Guide to Building Your Corpus
Pune's IT and auto generation is nearing 50 without a government pension behind it. Here is a step-by-step way to size your corpus and combine EPF, PPF, NPS and mutual funds, with 2026 rates.
Money n Wealth · Insights
NPS vs Mutual Funds for Retirement
2026 · Retirement Planning
NPS vs Mutual Funds for Retirement: The Complete Comparison Guide
NPS gives tax breaks and enforced discipline; mutual funds give control and liquidity. This 2026 comparison covers the new 80:20 NPS exit rule, equity limits, tax sections and how to split money between the two.
Money n Wealth · Insights
Retirement Planning in India
2026 · Retirement Planning
Retirement Planning in India: How Much Corpus You Need (2026 Guide)
Starting at 40 instead of 30 can more than triple the monthly SIP needed for the same retirement goal. Work out your corpus, compare EPF, PPF, NPS and SCSS at current rates, and avoid the common mistakes.