Five Years to Retirement: The Pre-Retirement Checklist for 2026
Last updated: 13 October 2026
Quick answer (Five Years to Retirement): A pre-retirement checklist for the last five years covers six jobs: confirm your corpus is enough, buy personal health cover while employed, clear all loans, cut equity gradually to about 50–55%, set up a bucket strategy so a crash never forces equity sales, and decide your EPF, NPS, SCSS and tax choices before the last salary.
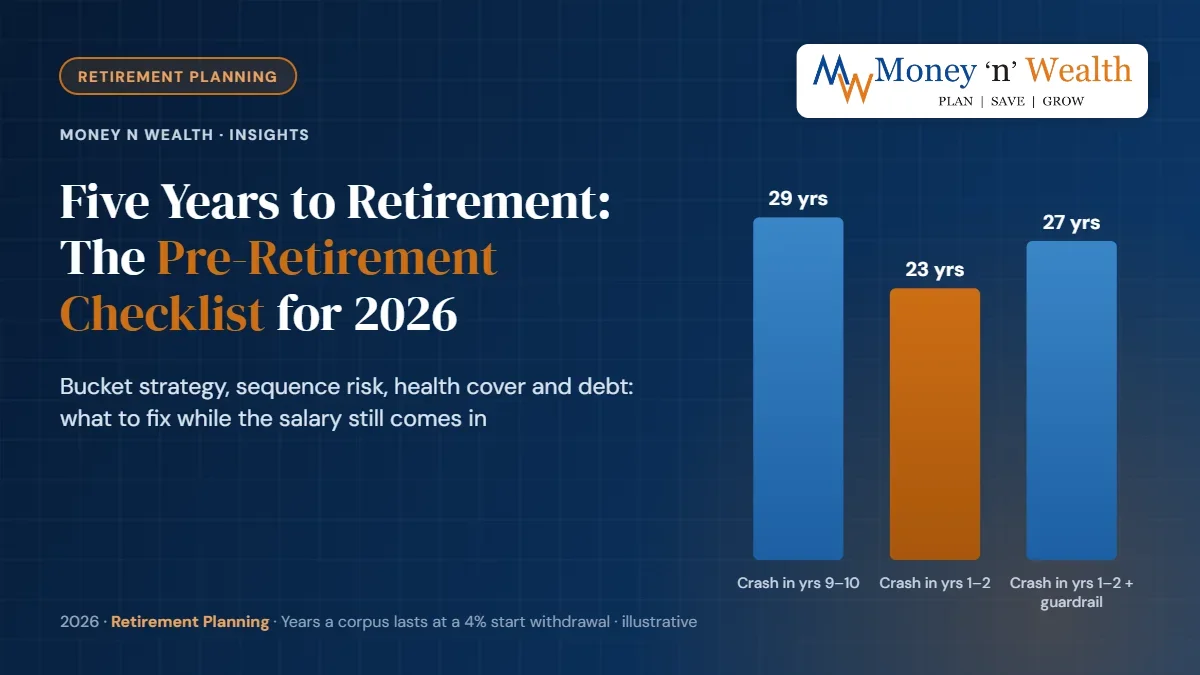
Last updated: 13 October 2026 Quick answer (Five Years to Retirement): A pre-retirement checklist for the last five years covers six jobs: confirm your corpus is enough, buy personal health cover while employed, clear all loans, cut equity gradually to about 50–55%, set up a bucket strategy so a crash never forces equity sales, and decide your EPF, NPS, SCSS and tax choices before the last salary. Key takeaways Sequence risk: in our example, bad returns early make the corpus run out at 81 instead of 86. Bucket 1: keep about three years of spending in SCSS, FDs and liquid funds. Health first: buy cover by 55; pre-existing disease waits are capped at 36 months. Debt-free: a ₹25 lakh loan over five years costs ₹51,593 a month; clear it before retiring. Withdrawal rate: aim for 3–3.5% of the corpus in year one, not 4.5%. Meera is 55 and works in finance at a Pune manufacturing company. She and her husband have ₹1.8 crore across EPF, mutual funds, PPF and FDs, and they save ₹75,000 a month. She plans to retire at 60. On paper, the plan looks fine. The danger is not the average return over the next 30 years. It is what happens in the five years either side of her last payslip, when the corpus is largest and her ability to recover from a mistake is smallest. Planners call this the "retirement red zone". This checklist walks through what to fix, year by year, with worked numbers. Five Years to Retirement: What should you do five years before retirement? A pre-retirement checklist is a set of financial, insurance and paperwork tasks timed to finish before your salary stops. The order matters: some tasks, such as health cover, are cheaper or only possible while you are employed and healthy. Pre-retirement checklist timeline for the five years before retirement in India Area Target by retirement day Why it matters Corpus Year-one withdrawal of 3–3.5% of corpus Higher rates leave little room for bad markets Debt Zero EMIs Fixed outflows force withdrawals in bad years Health cover Personal floater plus super top-up Group cover ends with the job Asset mix About 50–55% equity, three years of income in safe assets Limits damage from a crash near retirement Paperwork Nominations, will, consolidated folios Saves family months of claims work Tax Regime chosen, Form 121 where eligible Avoids unnecessary TDS on interest Is your corpus enough? Re-run the numbers at 55 At 55, the uncertainty is much smaller than at 40, so the maths is worth doing properly. Meera's household spends ₹90,000 a month. At 6% inflation, that becomes about ₹1.2 lakh a month, or ₹14.45 lakh a year, at 60. If her ₹1.8 crore grows at 9% and she keeps saving ₹75,000 a month, she could have about ₹3.33 crore at 60. Her first-year withdrawal would then be 4.3% of the corpus. That is higher than it looks. Bengen's 1994 study found 4% survived every 30-year period in US history, but Indian research reported by Business Standard suggests a lower safe rate of about 3–3.5% because of higher inflation. Our SWP guide (/insights/swp-systematic-withdrawal-plan-guide) covers this research in detail. Three ways to fix a thin corpus while there is still time Work a little longer: each extra year adds savings, adds growth and removes a year of withdrawals. Cut the retirement budget: identify what will genuinely stop (commuting, EMIs, children's costs). Plan part-time income: even ₹30,000 a month for the first five years of retirement takes pressure off the corpus during the riskiest period. Our retirement corpus guide (/insights/retirement-planning-guide-india) and "Is ₹1 crore enough?" analysis (/insights/is-1-crore-enough-to-retire-india-magic-number) explain how to size the target. What is sequence of returns risk, and why does it peak now? Sequence of returns risk is the danger that poor market returns arrive just before or just after you start withdrawing. Two retirees can earn the same average return over 30 years and get very different outcomes, because withdrawals during a fall sell more units at low prices, and those units never recover. We ran Meera's ₹3.33 crore through two identical sets of returns in opposite order. In both, the first 10 years include a −18% and a −6% year, followed by 8.5% a year. Sequence of returns risk chart: a retirement corpus with early losses runs out at 81, with late losses at 86 With the bad years first, her money runs out at 81. With the same bad years in her late 60s, it lasts to 86. Nothing changed except the order. A crash at 59 or 61 does far more damage than the same crash at 70. How much difference does the withdrawal rate make? Year-one withdrawal Bad years first Bad years later Bad years first, with guardrail 3.0% 35 years 42 years 42 years 3.5% 28 years 34 years 33 years 4.0% 23 years 29 years 27 years 4.3% 21 years 26 years 24 years The "guardrail" here is simple: skip the inflation increase in any year after a negative return. That small act of flexibility recovers most of the damage from a bad start. It is one reason a written withdrawal rule is worth more than a precise forecast. (Money n Wealth calculation; same assumptions as the chart, withdrawals otherwise rising 6% a year.) How do you reduce equity before retirement without hurting returns? Cut equity gradually, not all at once, and not to zero. A retirement may last 30 years, so the corpus still needs growth. A common glide path goes from about 65% equity at 55 to 50–55% at 60, and holds there. Chart showing how equity allocation in the five years before retirement changes the loss from a market crash The chart shows why. On a ₹3.6 crore portfolio at 59, a 35% equity fall costs ₹88 lakh at 75% equity but ₹43 lakh at 45% equity. The lower figure is recoverable; the higher one may force a later retirement. Move money in steps, for example a fifth of the planned shift each year. Use the annual review to rebalance, and harvest long-term equity gains of up to ₹1.25 lakh a year tax-free while you do it. Our capital gains tax guide (/insights/capital-gains-tax-mutual-funds-2026) explains the 12.5% LTCG rule. How does the bucket strategy work in retirement? The bucket strategy splits a retirement corpus by when you will need the money. Near-term income sits in safe, liquid assets; long-term money stays in equity. The point is behavioural as much as financial: when markets fall, you spend from Bucket 1 and leave equity alone to recover. Bucket strategy for retirement showing three buckets for near-term income, medium-term debt and long-term equity Filling the buckets: Meera at 60 Bucket 1 (₹46 lakh, years 1–3): SCSS pays 8.2% for October–December 2026 on up to ₹30 lakh per person, with quarterly payouts. Add an FD ladder and a liquid fund for the monthly SWP. Bucket 2 (₹1.02 crore, years 4–10): short-duration and corporate bond funds, RBI Floating Rate Savings Bonds (8.05% for July–December 2026), and conservative hybrid or arbitrage funds. Bucket 3 (₹1.85 crore, year 11 onwards): diversified equity funds. Left alone in bad years; after good years, profits move to Bucket 2. Start building Bucket 1 from about 57, using maturing FDs, bonuses and some EPF. That way you are not forced to sell equity in the exact year you retire. Our guides to SCSS (/insights/senior-citizens-savings-scheme-scss-guide) and FD vs SCSS vs RBI bonds (/insights/senior-citizen-fd-vs-scss-vs-rbi-floating-rate-bonds) compare the Bucket 1 and 2 options, and retirement income strategy (/insights/retirement-income-strategy-india) shows the monthly cash flow. Why buy health insurance before retirement? Group health cover usually ends on your last working day. Buying a personal policy at 55, while still covered at work, gives you time to clear waiting periods before you need the cover most. Waiting periods: IRDAI's May 2024 master circular capped pre-existing disease waits at 36 months. Buy at 55 and they are over by 58. No age cap: insurers must now offer cover at any age, but underwriting, loadings and co-pays are stricter later. Premium increases: since January 2025, insurers need IRDAI approval to raise premiums for those aged 60-plus by more than 10% a year. Tax and GST: individual health premiums are GST-free since 22 September 2025; seniors can deduct up to ₹50,000 under section 126 in the old regime. A base floater of ₹10–15 lakh plus a super top-up is a common structure. See our guides to super top-up plans (/insights/super-top-up-health-insurance) and health insurance for senior citizens (/insights/health-insurance-for-parents-senior-citizens) . What about term insurance? Term cover replaces income for dependants. If your corpus can already support your spouse, you may not need it after retirement. Keep it until loans are cleared and the corpus is in place. Should you clear all debt before retiring? Yes, in almost every case. An EMI is a fixed claim on your income that does not pause when markets fall. A ₹25 lakh home loan over its last five years at 8.75% costs ₹51,593 a month, more than a third of Meera's planned retirement spending. Use bonuses and maturing deposits to prepay in the final five years. Do not take a new car loan or a loan for a child's wedding close to retirement without modelling its effect. Our prepay or invest guide (/insights/prepay-home-loan-or-invest) works through the trade-off. What should you decide about EPF, NPS, gratuity and SCSS? Benefit Key rule (as of October 2026) Decision to make EPF Withdrawal after 5 years' continuous service is tax-free; account becomes inoperative 36 months after money becomes payable When to claim, and where the money goes next NPS Non-government subscribers can take up to 80% as lump sum; at least 20% of a corpus above ₹12 lakh buys an annuity; deferral possible Lump sum, annuity type and timing Gratuity Tax-free up to ₹20 lakh over a lifetime for private employees Check the employer's calculation Leave encashment Tax-free up to ₹25 lakh for non-government employees, from 1 April 2023 Count accumulated leave SCSS From 60, or 55–60 if invested within 3 months of retirement benefits; ₹30 lakh limit How much of Bucket 1 to lock in On NPS, only 60% of the corpus is clearly tax-free at exit, so the extra 20% lump sum may be taxable. Read NPS after 60 (/insights/nps-after-60-withdraw-defer-or-continue) before choosing. How will your income be taxed after retirement? Many retirees pay little tax. Under the new regime (section 202), the section 156 rebate makes income up to ₹12 lakh tax-free, and pension taxed as salary gets the ₹75,000 standard deduction. SWP withdrawals from equity funds are taxed only on the gain portion, at 12.5% above ₹1.25 lakh for long-term gains. Two practical points. Residents aged 60-plus without business income do not need to pay advance tax. And if your total income is below the taxable limit, submit Form 121 (which replaced Forms 15G and 15H) to avoid TDS on FD interest above ₹1 lakh a year. Our senior citizen tax planning guide (/insights/senior-citizen-tax-planning-interest-pension-rent) and retirement withdrawal strategies (/insights/retirement-tax-planning-five-withdrawal-strategies) go further. The paperwork that saves your family months Consolidate mutual fund folios, old PF accounts and dormant bank accounts. See consolidating scattered investments (/insights/consolidate-scattered-investments-and-policies) . Update nominations on every folio, demat account, bank account and policy. Write or update a will, and tell your spouse where every document is. Prepare a one-page list of accounts, policies and contacts. Related reading SWP explained: monthly income from mutual funds (/insights/swp-systematic-withdrawal-plan-guide) Retirement income for 25 years: pension, rent or SWP? (/insights/retirement-income-pension-rent-or-swp-25-years) Retirement planning at 40: how to catch up (/insights/starting-retirement-planning-at-40) Retirement planning for couples (/insights/retirement-planning-for-couples-india) NPS payout choices: RIS vs annuity vs systematic withdrawal (/insights/nps-payout-ris-annuity-systematic-withdrawal) Retirement planning help in Pune (/insights/retirement-planner-in-pune) Frequently Asked Questions How much equity should I hold five years before retirement? There is no single figure, but many plans move from about 60–65% equity at 55 towards 50–55% at 60. A retirement can last 30 years, so going to zero equity usually leaves the corpus short. The safer approach is to hold about three years of spending in safe assets, so you never sell equity during a crash. What is a safe withdrawal rate for retirement in India? Research on Indian data suggests about 3–3.5% of the corpus in year one, raised with inflation, is a prudent range for a 30-year retirement. The US "4% rule" assumes lower inflation. In our example, a 4.3% start lasted only 21 years after a bad start, while 3% lasted 35 years. What is the bucket strategy for retirement? It divides the corpus into three parts: one to three years of spending in liquid funds, SCSS or FDs; the next several years in short-term debt and hybrid funds; and the rest in equity for long-term growth. Income comes from the first bucket, which is refilled from the others, so a market fall does not force equity sales. Should I buy health insurance before retiring even if I have company cover? Yes. Group cover usually ends when you leave. Buying a personal policy around 55 lets pre-existing disease waiting periods, capped at 36 months by IRDAI, run out while you are still covered at work. Premiums and underwriting are generally easier while you are younger and healthier. Should I withdraw my EPF immediately on retirement? Not necessarily on day one, but do not leave it indefinitely. Under the EPF Scheme, an account becomes inoperative 36 months after money becomes payable, and interest then stops. Withdrawal after five years' continuous service is tax-free. Many retirees claim it in the first year and move it into Bucket 1 and Bucket 2. Is it better to take the NPS lump sum or buy a larger annuity? It depends on your need for guaranteed income and tax. Non-government subscribers can take up to 80% as a lump sum, but only 60% is clearly tax-free. Using more for an annuity gives lifelong guaranteed income but locks the money. Many retirees combine a modest annuity with an SWP. What is sequence of returns risk? It is the risk that weak returns arrive early in retirement, when withdrawals sell more units at low prices. Two retirees with the same average return can see very different outcomes. In our example, the same returns in reverse order changed the corpus lifespan from 21 to 26 years. Sources: Bengen (1994), Journal of Financial Planning (https://freefincal.com/wp-content/uploads/2023/10/Bengen1.pdf) ; Business Standard on Indian safe withdrawal rates (https://www.business-standard.com/amp/finance/personal-finance/make-your-retirement-portfolio-last-longer-withdraw-funds-conservatively-124022901095_1.html) ; Business Standard on IRDAI's 10% premium cap (https://www.business-standard.com/finance/insurance/irdai-caps-senior-cctizens-s-health-premium-increase-at-10-per-annum-125013001602_1.html) ; IRDAI health insurance master circular, May 2024 (summary) (https://www.basunivesh.com/irdas-new-health-insurance-changes-2024/) ; Income Tax Department, section 126 (https://www.incometaxindia.gov.in/w/section-126-92) ; RBI, Floating Rate Savings Bonds rate (https://www.rbi.org.in/scripts/BS_PressReleaseDisplay.aspx?prid=63065) ; CBDT notification 31/2023 on leave encashment (https://www.gconnect.in/personal-income-tax/increased-limit-tax-exemption-leave-encashment-non-govt-salaried-employees.html) ; Outlook Money on PFRDA NPS exit rules (https://www.outlookmoney.com/retirement/pension/pfrda-overhauls-nps-exit-rules-big-update-on-exit-age-vesting-period) . Worked examples are Money n Wealth calculations. Retiring in the next five years? The order of your decisions on buckets, NPS, EPF and tax can add years to your corpus, and each family's mix is different. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
How much equity should I hold five years before retirement?
There is no single figure, but many plans move from about 60–65% equity at 55 towards 50–55% at 60. A retirement can last 30 years, so going to zero equity usually leaves the corpus short. The safer approach is to hold about three years of spending in safe assets, so you never sell equity during a crash.
What is a safe withdrawal rate for retirement in India?
Research on Indian data suggests about 3–3.5% of the corpus in year one, raised with inflation, is a prudent range for a 30-year retirement. The US "4% rule" assumes lower inflation. In our example, a 4.3% start lasted only 21 years after a bad start, while 3% lasted 35 years.
What is the bucket strategy for retirement?
It divides the corpus into three parts: one to three years of spending in liquid funds, SCSS or FDs; the next several years in short-term debt and hybrid funds; and the rest in equity for long-term growth. Income comes from the first bucket, which is refilled from the others, so a market fall does not force equity sales.
Should I buy health insurance before retiring even if I have company cover?
Yes. Group cover usually ends when you leave. Buying a personal policy around 55 lets pre-existing disease waiting periods, capped at 36 months by IRDAI, run out while you are still covered at work. Premiums and underwriting are generally easier while you are younger and healthier.
Should I withdraw my EPF immediately on retirement?
Not necessarily on day one, but do not leave it indefinitely. Under the EPF Scheme, an account becomes inoperative 36 months after money becomes payable, and interest then stops. Withdrawal after five years' continuous service is tax-free. Many retirees claim it in the first year and move it into Bucket 1 and Bucket 2.
Is it better to take the NPS lump sum or buy a larger annuity?
It depends on your need for guaranteed income and tax. Non-government subscribers can take up to 80% as a lump sum, but only 60% is clearly tax-free. Using more for an annuity gives lifelong guaranteed income but locks the money. Many retirees combine a modest annuity with an SWP.
What is sequence of returns risk?
It is the risk that weak returns arrive early in retirement, when withdrawals sell more units at low prices. Two retirees with the same average return can see very different outcomes. In our example, the same returns in reverse order changed the corpus lifespan from 21 to 26 years.
Retiring in the next five years?
The order of your decisions on buckets, NPS, EPF and tax can add years to your corpus, and each family's mix is different. Talk to Money n Wealth for a free portfolio review.