Retirement Planning at 40: How to Catch Up If You Started Late (2026)
Last updated: 13 October 2026
Quick answer: Retirement planning at 40 is not too late, but it is more expensive. At an assumed 10% return, the SIP needed to build the same corpus by 60 is about 2.9 times what it would be from 30. Close the gap with five levers: count your EPF, raise the SIP 10% every year, use employer NPS, keep enough equity, and consider working two or three years longer.
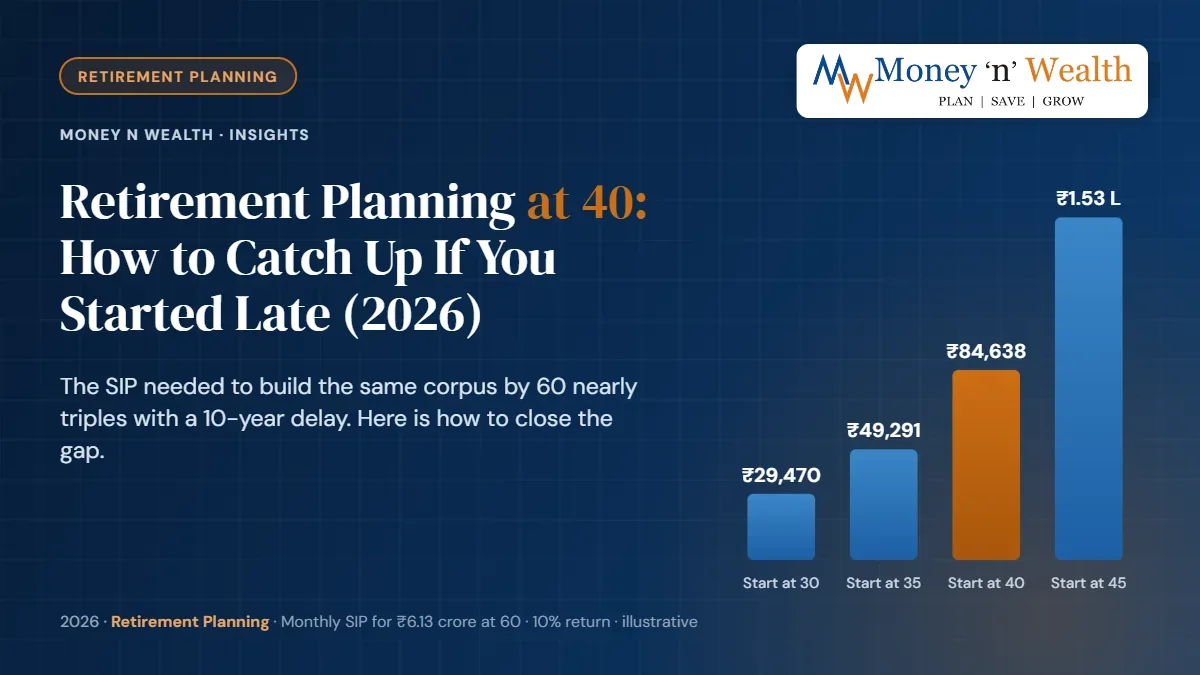
Last updated: 13 October 2026 Quick answer: Retirement planning at 40 is not too late, but it is more expensive. At an assumed 10% return, the SIP needed to build the same corpus by 60 is about 2.9 times what it would be from 30. Close the gap with five levers: count your EPF, raise the SIP 10% every year, use employer NPS, keep enough equity, and consider working two or three years longer. Key takeaways Cost of delay: ₹29,470 a month from 30 vs ₹84,638 from 40 for the same ₹6.13 crore at 60. Step-up power: a 10% yearly increase cuts the starting SIP at 40 by more than half. EPF counts: in our example, EPF alone covers 38% of the target corpus. Two more years: retiring at 62 instead of 60 lowers the required SIP by about 31%. Combined levers: step-up plus retiring at 62 takes the starting SIP from ₹41,323 to ₹12,534. Ravi is 40, an engineering manager in Hinjewadi, with a home loan, a 10-year-old daughter and about ₹30 lakh saved across EPF and a few mutual funds. Last month a colleague showed him a retirement calculator. The number it threw up, more than ₹6 crore, made him close the tab. That reaction is common, and it is the wrong one. Retirement planning at 40 starts from a weaker position than at 30, but a 40-year-old typically earns more, already has an EPF balance, and still has 20 years of compounding ahead. This guide works through the maths in rupees, shows how much a late start really costs, and ranks the levers that close the gap. Is 40 too late to start retirement planning? No. Twenty years is long enough for equity compounding to do most of the heavy lifting. What changes is the size of the monthly commitment. A late start means each rupee has less time to grow, so you need more rupees. The table below shows the monthly SIP needed to build the same corpus, ₹6.13 crore by age 60, starting from zero at different ages. We assume a 10% annual return, roughly what a portfolio of about 70% equity and 30% debt might earn over long periods, though actual returns will vary. Start age Years to 60 Flat monthly SIP Starting SIP if raised 10% a year 30 30 ₹29,470 ₹10,186 35 25 ₹49,291 ₹19,686 40 20 ₹84,638 ₹39,631 45 15 ₹1,52,574 ₹85,102 Retirement planning at 40 chart comparing the monthly SIP needed to build the same retirement corpus starting at 30, 35, 40 and 45 Starting at 40 instead of 30 multiplies the required SIP by about 2.9 times. Waiting five more years, to 45, nearly doubles it again. The real cost of delay is not the 10 lost years of contributions; it is the 10 lost years of compounding on everything you would have invested. The good news is that almost nobody actually starts at zero at 40. Your EPF balance, any PPF, ELSS or old SIPs, and future EPF contributions all count. Once you include them, the picture usually looks far less alarming. How much retirement corpus do you need if you are 40 today? A retirement corpus is the pool of investments that must pay your living costs from the day your salary stops until the end of your life, rising with inflation every year. Three inputs drive it: today's spending, inflation until and during retirement, and the return the money earns after you retire. Worked example: Ravi's number Ravi's household spends ₹75,000 a month today, excluding the home loan EMI that ends before retirement. Our assumptions: Inflation: 6% a year. India's CPI inflation was 5.54% in September 2026, and lifestyle and medical costs often rise faster. Retirement: at 60, with money planned to last to 85 (25 years). Return after retirement: 7.5% a year on a conservative mix. Return before retirement: 10% on mutual funds, 8.25% on EPF (the rate declared for FY 2025-26). At 6% inflation, ₹75,000 a month today becomes about ₹2.4 lakh a month at 60. Funding that for 25 years, rising 6% every year, needs about ₹6.13 crore at retirement. That is roughly 21 times his first year's spending. If Ravi plans to age 90 instead, the target rises to about ₹7.12 crore. Our guide on whether ₹1 crore is enough to retire (/insights/is-1-crore-enough-to-retire-india-magic-number) explains why multiples of 25 to 33 times expenses are common planning ranges. What he already has working for him Ravi has ₹18 lakh in EPF and ₹12 lakh in equity and hybrid funds. His basic pay is ₹70,000 a month, so about ₹15,550 a month flows into EPF from his and his employer's share, after ₹1,250 is diverted to the EPS pension scheme. We assume that rises 6% a year with his pay. Retirement corpus at 40 worked example showing contributions from EPF, existing mutual funds and new SIP By 60, EPF could reach about ₹2.33 crore and his existing funds about ₹81 lakh. That leaves a gap of about ₹2.99 crore, which needs a monthly SIP of ₹41,323 at 10% for 20 years. Ravi's take-home pay is ₹1.8 lakh, so this is demanding but possible. It is also far less than the ₹84,638 a zero-start 40-year-old would need. Our EPF calculator guide (/insights/epf-calculator-eps-pension-guide) shows how to project your own PF balance. How much SIP do you need at 40 for retirement? The five levers Once the gap is known, you can attack it from five directions. The chart shows how each one changes Ravi's starting SIP, with everything else unchanged. Bar chart of levers for late retirement planning at 40: step-up SIP, lower spending and retiring later reduce the monthly SIP 1. Step up the SIP every year Your income at 40 will probably keep rising for another 10 to 15 years. A SIP that rises 10% a year needs a starting amount of only ₹19,349 instead of ₹41,323, because later, larger instalments do more of the work. Even a 5% step-up cuts the starting figure to ₹29,046. Most fund houses let you set an automatic top-up when you register the SIP. Our step-up SIP calculator guide (/insights/step-up-sip-calculator-guide) has the full tables. The catch: a step-up only works if you actually stick to it. If your pay stagnates, the plan falls behind, so review it each year. 2. Work two or three years longer Retiring at 62 instead of 60 does three things at once: two more years of contributions, two more years of compounding, and two fewer years of withdrawals. Ravi's required SIP drops to ₹28,579. At 63 it falls to ₹22,956. Even part-time or consulting income in your early 60s has a similar effect. 3. Plan for a leaner retirement budget If retirement spending can be 15% lower than today's in real terms (no commuting, no EMIs, children independent), the corpus target falls to about ₹5.21 crore and the SIP to ₹28,627. Be careful here: healthcare and travel often rise in early retirement. Do not assume cuts you will not make. 4. Keep enough equity Many people who start late become cautious and park money in FDs. That makes the gap worse. At a 9% return, Ravi needs ₹48,589 a month; at 11%, ₹34,717. With 20 years to go, a 60–75% equity allocation is common, cutting back gradually in the last five years. SEBI's new life cycle funds (/insights/life-cycle-funds-sebi-new-category) automate that glide path, though they suit a single goal date better than a 25-year retirement. 5. Combine them Levers multiply. A 10% step-up and retiring at 62 together bring Ravi's starting SIP down to ₹12,534 , a 70% reduction. Add employer NPS and it falls further. This is why a late starter should not be discouraged by a headline number: the combination is what matters. How EPF, VPF and NPS help a late starter For salaried 40-year-olds, retirement wrappers offer tax efficiency and forced discipline. Each has trade-offs. Option Return type Tax angle (as of October 2026) Main limitation EPF Declared rate, 8.25% for FY 2025-26 Interest on own contributions above ₹2.5 lakh a year is taxable Fixed-income only; no equity growth VPF Same as EPF Counts in the same ₹2.5 lakh limit Same as EPF; voluntary but sticky Employer NPS Market-linked; you choose equity share Deductible up to 14% of basic plus DA under the new regime (section 124) At normal exit, at least 20% of a corpus above ₹12 lakh buys an annuity Own NPS (₹50,000 extra) Market-linked Deduction under section 124 in the old regime only Little benefit if you are on the new regime Mutual fund SIP Market-linked Equity LTCG taxed at 12.5% above ₹1.25 lakh a year No lock-in, so discipline is on you Employer NPS: the one deduction left in the new regime Since the Finance (No. 2) Act, 2024, private-sector employees on the new regime can have up to 14% of basic plus DA paid into NPS by the employer, tax-free in their hands. Under the Income-tax Act, 2025 this sits in section 124. If Ravi's employer restructures his pay to put 14% of his ₹70,000 basic into NPS, that is ₹9,800 a month. At a 31.2% marginal rate, the tax saved is about ₹36,700 a year, money that can go straight into the plan. Total employer contributions to EPF, NPS and superannuation above ₹7.5 lakh a year are taxed as a perquisite. The trade-off is liquidity. Under PFRDA's exit rules notified on 15 December 2025, a non-government subscriber exiting normally at 60 can take up to 80% as a lump sum, but at least 20% of a corpus above ₹12 lakh must buy an annuity. Leaving before 60 forces 80% into an annuity. Our NPS vs mutual funds comparison (/insights/nps-vs-mutual-funds-complete-comparison-guide) and NPS changes in 2026 (/insights/nps-changes-2026-investor-guide) cover the detail. VPF: useful, but do not over-rely on it VPF earns the EPF rate with sovereign-like safety. It is good for the debt part of your portfolio. But a 40-year-old who puts the entire catch-up into VPF gives up equity growth. Our EPF and VPF rules guide (/insights/epf-vpf-rules-withdrawal-tax-2026) explains the ₹2.5 lakh interest limit and the 2026 withdrawal rules. Step-by-step retirement planning at 40 catch-up checklist for Indian investors What mistakes do people make when starting retirement planning late? Chasing high returns to catch up. Small-cap-heavy portfolios, F&O trading or "guaranteed" schemes add risk you cannot afford at 40-plus. A disciplined 10% beats a hoped-for 18%. Raiding EPF for other goals. The 2026 rules make partial withdrawal easier. A ₹5 lakh withdrawal at 40 could have grown to about ₹20.8 lakh by 58 at 8.25%. Mixing retirement with children's education. Education comes first in time, so it tends to swallow retirement money. Run two separate goals, as in our child education planning guide (/insights/child-education-planning-guide-india) . Skipping insurance. Without term and health cover, one illness or death can undo a decade of catch-up. Many people discover gaps in group cover only at a claim. Ignoring the spouse's money. Couples should plan one combined corpus; see retirement planning for couples (/insights/retirement-planning-for-couples-india) . Waiting for the "right time". Every year of delay from 40 raises the required SIP by roughly 12–14%. How should a 40-year-old invest for retirement? A simple, robust structure for a 20-year horizon: Core equity (50–60% of the portfolio): index funds or diversified large-cap and flexi-cap funds for the bulk of the SIP. Satellite equity (10–15%): mid- or small-cap exposure, sized so a 40% fall would not make you quit. Debt (25–35%): EPF, VPF and PPF usually cover this already. Check before adding debt funds. Gold (5–10%, optional): through ETFs or gold funds, as a diversifier. From about 55, start shifting gradually towards debt and set up an income structure. Our five-years-to-retirement checklist (/insights/five-years-to-retirement-checklist) covers that phase, and the SWP guide (/insights/swp-systematic-withdrawal-plan-guide) explains how the corpus becomes a monthly income. You can test your own numbers on our retirement and SIP calculators (/tools) . Global evidence supports this structure. Target-date funds in the US and lifecycle defaults in many pension systems follow the same pattern: high equity while young, then a glide path to safer assets near retirement. India's EPF and NPS give you the fixed-income and pension pieces; mutual funds supply the growth. Related reading Retirement planning in India: how much corpus do you need? (/insights/retirement-planning-guide-india) Your FIRE number: how much you need to retire early (/insights/fire-number-retire-early-india) Step-up SIP: what a 10% annual increase does (/insights/step-up-sip-calculator-guide) What to do with a bonus, inheritance or windfall (/insights/bonus-inheritance-windfall-what-to-do) Term insurance: how much cover you need (/insights/term-insurance-advisor-pune) Open or review NPS with Money n Wealth (/products/nps) Frequently Asked Questions Can I retire comfortably if I start saving at 40? Yes, in most cases, if you save seriously and use the right levers. A 40-year-old usually has 20 working years left, an EPF balance and rising income. Combining a SIP with an annual 10% step-up, employer NPS and a retirement age of 60–62 typically closes the gap. The earlier you start within your 40s, the lower the monthly commitment. How much should I save per month for retirement at 40? It depends on your spending, existing savings and target age. In our example, a household spending ₹75,000 a month with ₹30 lakh saved needs a SIP of about ₹41,300 a month, or about ₹19,300 rising 10% a year, at a 10% return. Someone starting from zero would need about ₹84,600 a month flat. Run your own numbers rather than relying on a rule of thumb. Is NPS good for retirement planning at 40? Employer NPS is attractive for new-regime taxpayers because up to 14% of basic plus DA is tax-free under section 124. Its downsides are limited liquidity and a mandatory annuity of at least 20% at normal exit for larger corpuses. It works well as one part of a retirement plan, alongside mutual funds that you can access more flexibly. Should I stop investing in my child's education to boost retirement? Not entirely. Run both goals, but protect retirement because there is no loan for retirement, while education loans exist. If money is tight, fund education first for the years closest to the expense, and use step-ups, bonuses and later pay rises to build up retirement savings. What return should I assume for retirement planning at 40? Use conservative figures: 10–11% for an equity-heavy portfolio over 20 years, 7–8% for debt, and the declared rate for EPF. Assume 6% inflation, higher for healthcare. Planning with optimistic returns produces a SIP that looks affordable but leaves you short at 60. Is it better to prepay my home loan or invest for retirement at 40? Usually a balance. If the loan rate after tax is well below the expected return on a diversified portfolio, investing generally builds more wealth over 20 years, but prepaying gives certainty. Many people prepay modestly while keeping the retirement SIP intact. Aim to be debt-free before retiring. Our guide on prepaying your home loan or investing (/insights/prepay-home-loan-or-invest) works through the numbers. How much term insurance should a 40-year-old have? A common starting point is 10–15 times annual income, plus outstanding loans, minus existing investments. Cover should last until your retirement corpus could support your family on its own, typically to age 60–65. Buying at 40 costs more than at 30, but it is still far cheaper than at 50. Sources: PIB: EPFO 239th CBT meeting, EPF rate 8.25% for FY 2025-26 (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2234502®=3&lang=1) ; Value Research on employer NPS deduction (https://www.valueresearchonline.com/stories/229044/employer-nps-deduction-new-tax-regime/) ; Taxheal: NPS deductions under the Income-tax Act 2025 (https://www.taxheal.com/?p=117319) ; Outlook Money on PFRDA NPS exit rules, December 2025 (https://www.outlookmoney.com/retirement/pension/pfrda-overhauls-nps-exit-rules-big-update-on-exit-age-vesting-period) ; MoSPI CPI release, September 2026 (https://www.mospi.gov.in/uploads/latestReleases/latest_release_1791800601071_643518af-5320-4e52-b78c-75c92b83885b_Press_Release_for_the_month_of_September,_2026.pdf) . Worked examples are Money n Wealth calculations. Started late and not sure how big your gap is? Your EPF, NPS, existing funds and family goals change the answer a lot, so a personal calculation beats a generic calculator. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
Can I retire comfortably if I start saving at 40?
Yes, in most cases, if you save seriously and use the right levers. A 40-year-old usually has 20 working years left, an EPF balance and rising income. Combining a SIP with an annual 10% step-up, employer NPS and a retirement age of 60–62 typically closes the gap. The earlier you start within your 40s, the lower the monthly commitment.
How much should I save per month for retirement at 40?
It depends on your spending, existing savings and target age. In our example, a household spending ₹75,000 a month with ₹30 lakh saved needs a SIP of about ₹41,300 a month, or about ₹19,300 rising 10% a year, at a 10% return. Someone starting from zero would need about ₹84,600 a month flat. Run your own numbers rather than relying on a rule of thumb.
Is NPS good for retirement planning at 40?
Employer NPS is attractive for new-regime taxpayers because up to 14% of basic plus DA is tax-free under section 124. Its downsides are limited liquidity and a mandatory annuity of at least 20% at normal exit for larger corpuses. It works well as one part of a retirement plan, alongside mutual funds that you can access more flexibly.
Should I stop investing in my child's education to boost retirement?
Not entirely. Run both goals, but protect retirement because there is no loan for retirement, while education loans exist. If money is tight, fund education first for the years closest to the expense, and use step-ups, bonuses and later pay rises to build up retirement savings.
What return should I assume for retirement planning at 40?
Use conservative figures: 10–11% for an equity-heavy portfolio over 20 years, 7–8% for debt, and the declared rate for EPF. Assume 6% inflation, higher for healthcare. Planning with optimistic returns produces a SIP that looks affordable but leaves you short at 60.
Is it better to prepay my home loan or invest for retirement at 40?
Usually a balance. If the loan rate after tax is well below the expected return on a diversified portfolio, investing generally builds more wealth over 20 years, but prepaying gives certainty. Many people prepay modestly while keeping the retirement SIP intact. Aim to be debt-free before retiring. Our guide on prepaying your home loan or investing works through the numbers.
How much term insurance should a 40-year-old have?
A common starting point is 10–15 times annual income, plus outstanding loans, minus existing investments. Cover should last until your retirement corpus could support your family on its own, typically to age 60–65. Buying at 40 costs more than at 30, but it is still far cheaper than at 50.
Started late and not sure how big your gap is?
Your EPF, NPS, existing funds and family goals change the answer a lot, so a personal calculation beats a generic calculator. Talk to Money n Wealth for a free portfolio review.