Is ₹1 Crore Enough to Retire in India? Finding Your Magic Number (2026)
Last updated: 21 October 2026 · Reviewed by the Money n Wealth research desk
Quick answer (₹1 Crore Enough to Retire): ₹1 crore is a meaningful sum, but for most Indian families it is not enough on its own for a 25 to 30-year retirement. At 6% inflation, ₹1 crore 25 years from now buys what about ₹23 lakh buys today, and a ₹50,000 monthly withdrawal that rises with prices would exhaust it in about 20 years. A better target is 25 to 33 times your annual expenses at retirement, adjusted for your health cover, other income and when you plan to stop working.
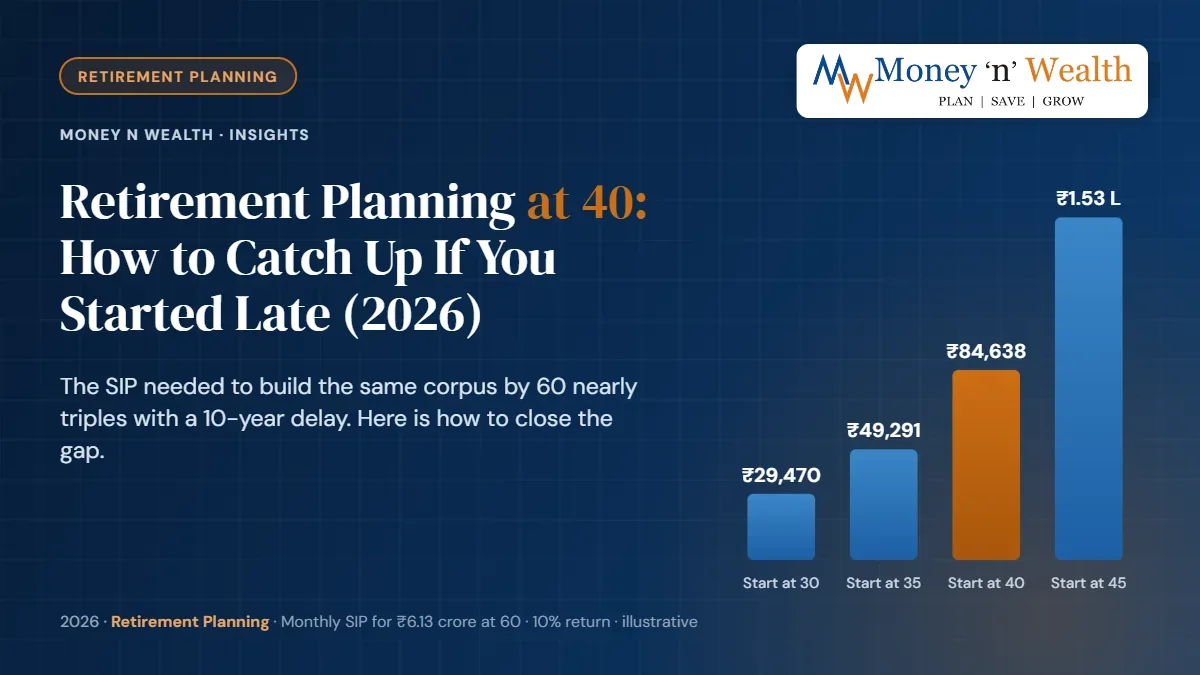
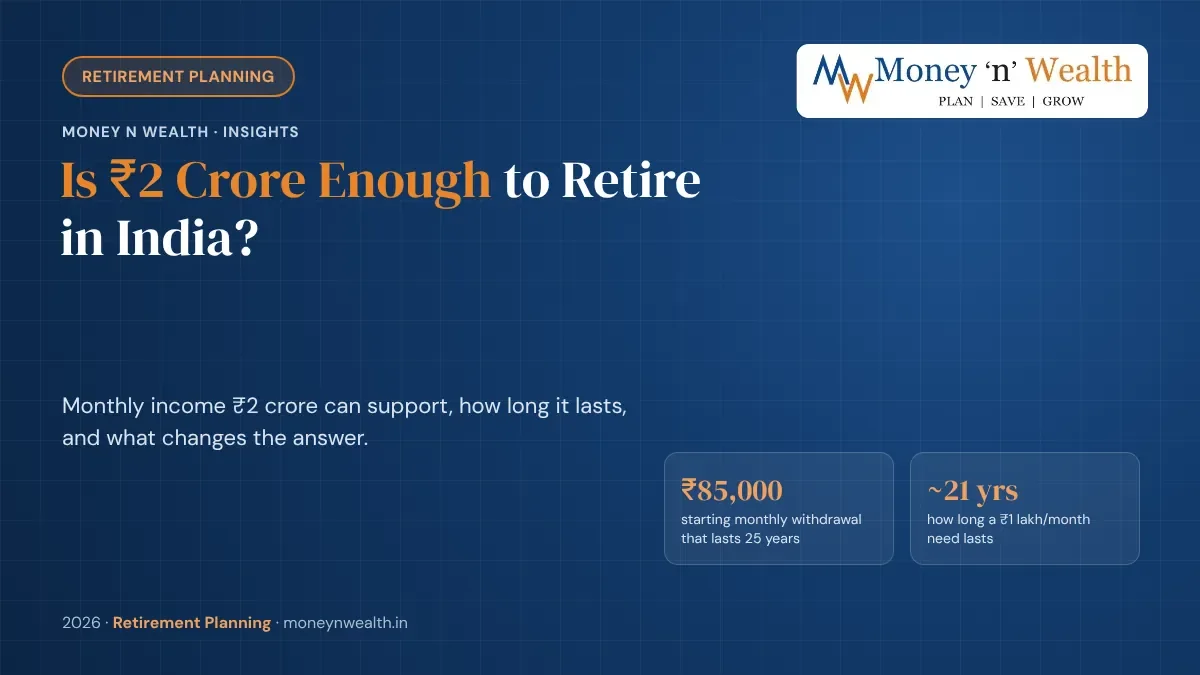
Last updated: 21 October 2026 · Reviewed by the Money n Wealth research desk Quick answer (₹1 Crore Enough to Retire): ₹1 crore is a meaningful sum, but for most Indian families it is not enough on its own for a 25 to 30-year retirement. At 6% inflation, ₹1 crore 25 years from now buys what about ₹23 lakh buys today, and a ₹50,000 monthly withdrawal that rises with prices would exhaust it in about 20 years. A better target is 25 to 33 times your annual expenses at retirement , adjusted for your health cover, other income and when you plan to stop working. Key takeaways Inflation is the real threat: India's CPI inflation rose to 5.54% in September 2026, a reminder that prices can climb quickly. Your number, not a headline number: start with today's monthly spend, project it to retirement, then multiply. Health costs need their own plan: medical inflation runs well above CPI, so insurance should sit outside the income corpus. Time is the biggest lever: a 10% yearly step-up can cut the starting SIP needed for a ₹6 crore goal by more than half. Why "is ₹1 crore enough to retire?" is the wrong first question For a generation of Indian savers, "one crore" became shorthand for financial security. It is a round number, it sounds large, and for many families it was once more than enough. The question keeps coming back in news reports and family conversations: what is the real "magic number"? The honest answer is that the number depends on three things a headline cannot know: how much you spend, how long your money must last and what it earns after you stop working. Over roughly a decade of helping individual investors in Pune and across India plan their retirement, the Money n Wealth team has seen the same pattern repeatedly: families who fixate on a round target often under-save, while families who start from their own expenses usually arrive at a workable plan sooner. What ₹1 crore will actually buy in the future Inflation quietly reduces what each rupee can buy. India's Ministry of Statistics (MoSPI) (https://www.mospi.gov.in/) reported headline CPI inflation of 5.54% for September 2026 on the new 2024-base series, up from 4.83% in August, with food inflation at 7.74% ( MoSPI press release (https://www.mospi.gov.in/uploads/latestReleases/latest_release_1791800601071_643518af-5320-4e52-b78c-75c92b83885b_Press_Release_for_the_month_of_September,_2026.pdf) ). Using a long-run planning assumption of 6% a year, here is what ₹1 crore is worth in today's money: Assumes 6% average annual inflation. Illustrative, not a forecast. When you retire Value of ₹1 crore in today's rupees What that means Today ₹1.00 crore Full purchasing power In 10 years about ₹56 lakh Roughly half its value lost In 15 years about ₹42 lakh Less than half In 25 years about ₹23 lakh Under a quarter of today's value So a 35-year-old who targets "₹1 crore at 60" is really targeting about ₹23 lakh of today's purchasing power. That is the gap the round number hides. How long does ₹1 crore last after retirement? The second test is longevity. If you retire today with ₹1 crore, earn 8% a year on the portfolio and raise your withdrawal by 6% each year to keep pace with prices, the corpus lasts roughly: Assumes 8% annual portfolio return, 6% annual increase in withdrawals and withdrawals at the start of each year. Real returns vary year to year. Monthly withdrawal in year one Approximate years ₹1 crore lasts ₹30,000 about 39 years ₹40,000 about 27 years ₹50,000 about 20 years ₹60,000 about 16 years With life expectancy for urban Indians who reach 60 now commonly stretching into the mid-80s and beyond, a plan that runs dry at 80 is a real risk. For a couple, the plan has to last until the second spouse's lifetime, which is often longer still. Our guide to retirement planning for couples (/insights/retirement-planning-for-couples-india) covers how to plan for both lifetimes. So what is the retirement "magic number"? A useful way to define the magic number is as a multiple of your annual expenses in the first year of retirement . It turns a vague goal into a figure you can calculate. Here is what the maths gives for different return assumptions, with withdrawals rising at 6% a year: Corpus needed as a multiple of first-year annual expenses, 6% inflation. Excludes a separate emergency or medical buffer. Post-retirement return 25-year retirement 30-year retirement 35-year retirement 7% 22.4× 26.3× 30.0× 7.5% 21.2× 24.7× 27.8× 8% 20.2× 23.2× 25.9× 9% 18.2× 20.6× 22.7× Add a margin for medical costs, home repairs, support for family members and years when markets disappoint, and a practical planning range is 25 to 33 times annual expenses . You may hear of the "4% rule" from the US, which equals 25 times. In India, where inflation has historically been higher, starting withdrawals closer to 3-3.5% of the corpus and reviewing them every year is the more cautious approach. A quick check: the 30x rule and where you live A simple Indian rule of thumb is a corpus of at least 30 times your annual expenses at retirement, which works out to a starting withdrawal of about 3.3% a year. A household spending ₹8 lakh a year would need about ₹2.4 crore. If you own your home, count only financial assets towards this number. Because living costs vary so much, the same lifestyle needs very different corpus sizes in different cities. One widely shared estimate by a chartered accountant puts a comfortable retirement at roughly ₹1.2 crore in a tier-3 town, about ₹3.5 crore in a tier-2 city such as Pune, and ₹8 to 9 crore or more in a metro. Treat these as starting points only, since they depend on your rent or home ownership, lifestyle and family support. Also set aside 10 to 15% of retirement spending for healthcare, which tends to rise faster than general inflation. Retirement corpus needed in a tier-3 town, tier-2 city and metro in India, with the 30x expenses rule Worked example: what a 35-year-old in Pune actually needs Consider Rahul (an illustrative profile), 35, whose household spends ₹50,000 a month today, excluding EMIs that will end before retirement. He plans to retire at 60. Project expenses: ₹50,000 growing at 6% for 25 years becomes about ₹2.15 lakh a month , or ₹25.8 lakh a year, at 60. Apply the multiple: for a 30-year retirement at 8% returns, 23.2 × ₹25.8 lakh ≈ ₹6 crore . At 7% returns, it rises to about ₹6.8 crore. Subtract what is already working for him: existing EPF, PPF, NPS and mutual fund balances, projected forward, reduce the gap. Convert the gap into a monthly plan: building ₹6 crore from scratch needs about ₹31,600 a month for 25 years at an assumed 12% return, or about ₹14,000 a month with a 10% annual step-up . The same family that would have aimed for "₹1 crore" needs roughly six times as much in future rupees. The good news is that the step-up approach makes it achievable on a normal salary path, as long as it starts early. Corpus needed at the date of retirement, assuming 8% return and 6% inflation. Figures are rounded and illustrative. Monthly expenses at retirement 25-year corpus 30-year corpus 35-year corpus ₹50,000 ₹1.21 crore ₹1.39 crore ₹1.56 crore ₹75,000 ₹1.81 crore ₹2.09 crore ₹2.33 crore ₹1,00,000 ₹2.42 crore ₹2.78 crore ₹3.11 crore ₹1,50,000 ₹3.63 crore ₹4.17 crore ₹4.67 crore Read the table from the row that matches your expected spending at the time you retire , not today. If you are 50 and spend ₹50,000 now, that becomes about ₹90,000 a month at 60. Five costs that most retirement calculations miss Healthcare: Aon projected India's medical cost trend at 11.5% for 2026 (https://www.aon.com/apac/in-the-press/asia-newsroom/2025/india-outpaces-global-average-with-2026-medical-trend-at-11-5-percent-aon-reports) , roughly double headline inflation. Health cover should be bought, and kept, before retirement. Our free insurance check-up (/free-insurance-checkup) reviews existing cover. Tax on withdrawals: interest, pension and capital gains are taxed differently. The order in which you draw from each source matters; see retirement tax planning: five withdrawal strategies (/insights/retirement-tax-planning-five-withdrawal-strategies) . Lifestyle in the early years: travel and hobbies often push spending up in the first decade of retirement, before it eases. Support for family: children's weddings, a parent's care or a child's home deposit frequently land after 60. Home upkeep and replacement: a paid-off home still needs repairs, society charges and, eventually, appliances and a car. How to turn a corpus into a monthly paycheque Reaching the number is half the job. The other half is drawing an income without being forced to sell growth assets after a market fall. Many retirees use a three-bucket structure: Instruments are examples, not recommendations. Suitability depends on your income, tax and risk profile. Bucket Holds Typical instruments 1. Income (years 1-3) Two to three years of expenses Savings, liquid and money market funds, short-term deposits 2. Stability (years 4-10) Medium-term needs Debt and hybrid funds, SCSS at 8.2% and POMIS at 7.4% (https://www.indiapost.gov.in/) (October-December 2026 rates), bonds 3. Growth (10+ years) Long-term inflation protection Diversified equity mutual funds, and for larger portfolios, PMS or SIFs where suitable Withdrawals then come from Bucket 1 through a mutual fund systematic withdrawal plan (SWP) (/products/mutual-funds) or interest income, while Buckets 2 and 3 refill it periodically. We explain the mechanics, with a ₹2 crore example, in how to turn your corpus into a monthly paycheque (/insights/retirement-income-strategy-india) , and compare pensions, rent and SWPs in retirement income for 25 years (/insights/retirement-income-pension-rent-or-swp-25-years) . For NPS subscribers, NPS payout choices (/insights/nps-payout-ris-annuity-systematic-withdrawal) and the seven NPS changes in 2026 (/insights/nps-changes-2026-investor-guide) are worth reading before you choose an exit route. A seven-step checklist to find your own number Write down today's monthly household spend, separating EMIs that will end before retirement. Project it to your retirement age at 6% inflation (use a higher rate for health and education costs). Pick a realistic horizon: plan to at least age 85-90, and to the younger spouse's age for couples. Multiply first-year retirement expenses by 25-33, depending on your return assumption and comfort with risk. Subtract the projected value of EPF, PPF, NPS, mutual funds and any assured pension or rent. Convert the gap into a SIP, ideally with an annual step-up linked to your salary increments. Review the plan every year and after any major life event; rebalance between equity and debt as retirement approaches. You can run these numbers with the free Money n Wealth financial planner (/planner) , which projects cash flow, assets and the retirement corpus year by year, or start with the shorter financial health check (/financial-health-check) . How Money n Wealth helps families plan retirement Money n Wealth is the investment distribution and planning practice of Predics Fintech Services Pvt Ltd, based in Thergaon, Pune. Over roughly a decade, the team has worked with individual investors and families on the full arc of retirement planning, from the first SIP to the first pension cheque. Here is what that experience looks like in practice: Goal-based planning first, products second: every engagement starts with expenses, goals and existing assets, using the same year-by-year projection approach as our online planner (/planner) . See our approach (/about/approach) . Research you can read: a growing library of more than 150 Insights articles, including detailed reviews of PMS strategies, AIFs, NPS rules and tax changes, written to explain the trade-offs rather than sell a product. Browse Financial Planning insights (/insights/category/financial-planning) or the full Insights library (/insights) . One place for the whole retirement toolkit: mutual funds and SWPs (/products/mutual-funds) , NPS (/products/nps) (via a tie-up with a PFRDA-registered Point of Presence), Specialised Investment Funds (/products/sif) , PMS (/products/pms) and AIFs (/products/aif) for larger portfolios, bonds (/products/bonds) , life and health insurance (/products/insurance) and tax consultation (/products/tax) . Regular reviews: a retirement plan is not a one-time document. Our portfolio review (/portfolio-review) checks allocation, overlap and withdrawal readiness as you move closer to retirement. Registered and transparent: AMFI-registered mutual fund distributor (ARN-121995) and APMI-registered PMS distributor (APRN07444). How we are paid is set out in our commission disclosure (/legal/commission) . If you would like a second look at your own number, book a free review (/start-free-review) or contact the team (/contact) . Disclaimer: Educational information only; not a personalised investment, tax or insurance recommendation. All projections are illustrative and based on stated assumptions; actual returns, inflation and outcomes will differ. Mutual fund investments are subject to market risks, read all scheme related documents carefully. Past performance is not indicative of future returns. Consult a qualified professional for your circumstances. Related reading on Money n Wealth Retirement planning guide for India (/insights/retirement-planning-guide-india) Retirement income strategy: the three-bucket approach (/insights/retirement-income-strategy-india) Retirement planning for couples (/insights/retirement-planning-for-couples-india) How big should your emergency fund be? (/insights/emergency-fund-guide-india) How to choose mutual funds: a portfolio-first framework (/insights/how-to-choose-mutual-funds-portfolio-framework) Browse all Money n Wealth Insights (/insights) Sources and further reading MoSPI: CPI press release for September 2026 (https://www.mospi.gov.in/uploads/latestReleases/latest_release_1791800601071_643518af-5320-4e52-b78c-75c92b83885b_Press_Release_for_the_month_of_September,_2026.pdf) India Post: small savings interest rates (Oct–Dec 2026) (https://www.indiapost.gov.in/) Aon: India 2026 medical trend at 11.5% (https://www.aon.com/apac/in-the-press/asia-newsroom/2025/india-outpaces-global-average-with-2026-medical-trend-at-11-5-percent-aon-reports) PFRDA: National Pension System (https://www.pfrda.org.in/) AMFI: Association of Mutual Funds in India (https://www.amfiindia.com/) SEBI Investor Education (https://investor.sebi.gov.in/) Frequently asked questions Is ₹1 crore enough to retire in India in 2026? For most urban families, no, unless expenses are modest or retirement is close. At 8% returns and 6% inflation, ₹1 crore lasts about 20 years if you withdraw ₹50,000 a month and raise it with inflation. It can work for someone retiring now with expenses near ₹30,000-35,000 a month, a paid-off home and separate health cover. What is the magic number for retirement in India? There is no single figure. A practical range is 25 to 33 times your annual expenses in the year you retire. The pure maths at 7-8% returns and 6% inflation gives roughly 23-26 times for a 30-year retirement; the higher end adds room for a longer life and medical costs. How much corpus do I need to retire with ₹50,000 a month? If you need ₹50,000 a month at the time you retire, a 30-year corpus is about ₹1.39 crore at 8% returns and 6% inflation, and about ₹1.58 crore at 7%. If you spend ₹50,000 a month today and retire in 25 years, the same lifestyle will cost about ₹2.15 lakh a month by then, which needs roughly ₹6 crore. Is the 4% rule valid for Indian retirees? The 4% rule comes from US data with lower inflation. In India, where inflation has averaged around 5-6% over long periods, a starting withdrawal of about 3-3.5% of the corpus, reviewed every year, is a more cautious starting point. How much SIP do I need to build a ₹6 crore retirement corpus in 25 years? At an assumed 12% annual return, about ₹31,600 a month held flat for 25 years, or about ₹14,000 a month if you raise the SIP by 10% every year. At 11% the figures rise to about ₹37,700 and ₹16,000. Returns are not guaranteed, so review the plan yearly. Should health insurance be part of retirement planning? Yes. Medical costs in India are rising faster than general inflation; Aon projected a medical cost trend of 11.5% for India in 2026. A separate family floater or senior health policy, bought well before retirement, keeps hospital bills from eating into the income corpus. Where should a retirement corpus be invested? Most retirees split it into buckets: two to three years of expenses in liquid or short-term debt, the next few years in debt and hybrid funds or government schemes such as SCSS, and the long-term bucket in diversified equity funds to beat inflation. The right mix depends on your other income, health and risk tolerance. {"@context": "https://schema.org", "@type": "FAQPage", "mainEntity": [{"@type": "Question", "name": "Is ₹1 crore enough to retire in India in 2026?", "acceptedAnswer": {"@type": "Answer", "text": "For most urban families, no, unless expenses are modest or retirement is close. At 8% returns and 6% inflation, ₹1 crore lasts about 20 years if you withdraw ₹50,000 a month and raise it with inflation. It can work for someone retiring now with expenses near ₹30,000-35,000 a month, a paid-off home and separate health cover."}}, {"@type": "Question", "name": "What is the magic number for retirement in India?", "acceptedAnswer": {"@type": "Answer", "text": "There is no single figure. A practical range is 25 to 33 times your annual expenses in the year you retire. The pure maths at 7-8% returns and 6% inflation gives roughly 23-26 times for a 30-year retirement; the higher end adds room for a longer life and medical costs."}}, {"@type": "Question", "name": "How much corpus do I need to retire with ₹50,000 a month?", "acceptedAnswer": {"@type": "Answer", "text": "If you need ₹50,000 a month at the time you retire, a 30-year corpus is about ₹1.39 crore at 8% returns and 6% inflation, and about ₹1.58 crore at 7%. If you spend ₹50,000 a month today and retire in 25 years, the same lifestyle will cost about ₹2.15 lakh a month by then, which needs roughly ₹6 crore."}}, {"@type": "Question", "name": "Is the 4% rule valid for Indian retirees?", "acceptedAnswer": {"@type": "Answer", "text": "The 4% rule comes from US data with lower inflation. In India, where inflation has averaged around 5-6% over long periods, a starting withdrawal of about 3-3.5% of the corpus, reviewed every year, is a more cautious starting point."}}, {"@type": "Question", "name": "How much SIP do I need to build a ₹6 crore retirement corpus in 25 years?", "acceptedAnswer": {"@type": "Answer", "text": "At an assumed 12% annual return, about ₹31,600 a month held flat for 25 years, or about ₹14,000 a month if you raise the SIP by 10% every year. At 11% the figures rise to about ₹37,700 and ₹16,000. Returns are not guaranteed, so review the plan yearly."}}, {"@type": "Question", "name": "Should health insurance be part of retirement planning?", "acceptedAnswer": {"@type": "Answer", "text": "Yes. Medical costs in India are rising faster than general inflation; Aon projected a medical cost trend of 11.5% for India in 2026. A separate family floater or senior health policy, bought well before retirement, keeps hospital bills from eating into the income corpus."}}, {"@type": "Question", "name": "Where should a retirement corpus be invested?", "acceptedAnswer": {"@type": "Answer", "text": "Most retirees split it into buckets: two to three years of expenses in liquid or short-term debt, the next few years in debt and hybrid funds or government schemes such as SCSS, and the long-term bucket in diversified equity funds to beat inflation. The right mix depends on your other income, health and risk tolerance."}}]}
Frequently Asked Questions
Is ₹1 crore enough to retire in India in 2026?
For most urban families, no, unless expenses are modest or retirement is close. At 8% returns and 6% inflation, ₹1 crore lasts about 20 years if you withdraw ₹50,000 a month and raise it with inflation. It can work for someone retiring now with expenses near ₹30,000-35,000 a month, a paid-off home and separate health cover.
What is the magic number for retirement in India?
There is no single figure. A practical range is 25 to 33 times your annual expenses in the year you retire. The pure maths at 7-8% returns and 6% inflation gives roughly 23-26 times for a 30-year retirement; the higher end adds room for a longer life and medical costs.
How much corpus do I need to retire with ₹50,000 a month?
If you need ₹50,000 a month at the time you retire, a 30-year corpus is about ₹1.39 crore at 8% returns and 6% inflation, and about ₹1.58 crore at 7%. If you spend ₹50,000 a month today and retire in 25 years, the same lifestyle will cost about ₹2.15 lakh a month by then, which needs roughly ₹6 crore.
Is the 4% rule valid for Indian retirees?
The 4% rule comes from US data with lower inflation. In India, where inflation has averaged around 5-6% over long periods, a starting withdrawal of about 3-3.5% of the corpus, reviewed every year, is a more cautious starting point.
How much SIP do I need to build a ₹6 crore retirement corpus in 25 years?
At an assumed 12% annual return, about ₹31,600 a month held flat for 25 years, or about ₹14,000 a month if you raise the SIP by 10% every year. At 11% the figures rise to about ₹37,700 and ₹16,000. Returns are not guaranteed, so review the plan yearly.
Should health insurance be part of retirement planning?
Yes. Medical costs in India are rising faster than general inflation; Aon projected a medical cost trend of 11.5% for India in 2026. A separate family floater or senior health policy, bought well before retirement, keeps hospital bills from eating into the income corpus.
Where should a retirement corpus be invested?
Most retirees split it into buckets: two to three years of expenses in liquid or short-term debt, the next few years in debt and hybrid funds or government schemes such as SCSS, and the long-term bucket in diversified equity funds to beat inflation. The right mix depends on your other income, health and risk tolerance.