Rent vs Buy in Pune 2026: A 10-Year Model With Real Numbers
Last updated: 13 October 2026
Quick answer (Rent vs Buy): On pure numbers, renting and investing the difference usually beats buying in Pune over 10 years when rent is only about 3% of the flat's price. In our model of a ₹90 lakh flat, the renter ends about ₹35 lakh ahead. Buying wins only if prices rise about 8% a year, or if the renter fails to invest steadily. Stability and a long stay can still justify buying.
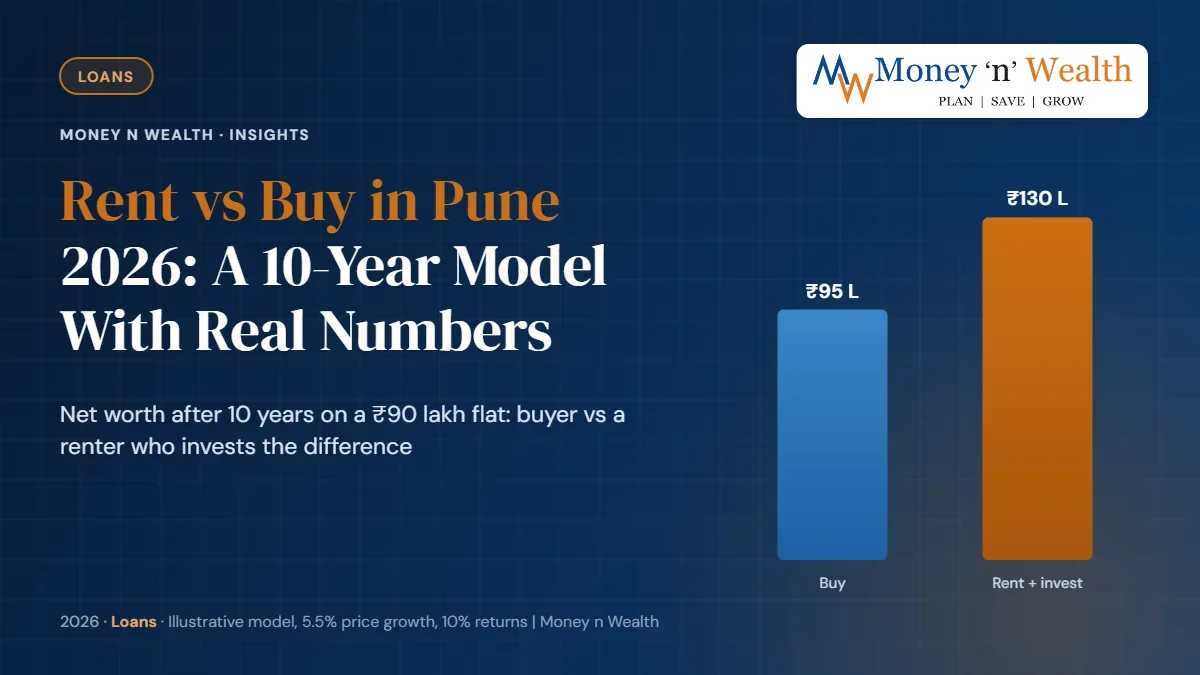
Last updated: 13 October 2026 Quick answer (Rent vs Buy): On pure numbers, renting and investing the difference usually beats buying in Pune over 10 years when rent is only about 3% of the flat's price. In our model of a ₹90 lakh flat, the renter ends about ₹35 lakh ahead. Buying wins only if prices rise about 8% a year, or if the renter fails to invest steadily. Stability and a long stay can still justify buying. Key takeaways Slow prices: Pune's NHB house price index rose 3.5% in the year to December 2025 (the latest NHB release), against 5.0% for 50 cities. Cash gap: buying costs about ₹68,000 a month in EMI and upkeep, against ₹25,000 rent for the same flat. Model result: renter ₹1.30 crore, buyer ₹95 lakh after 10 years, at 5.5% price growth and 10% returns. Behaviour decides: if the renter invests only half the gap, the two end level. Rule of thumb: rent below 3% of price favours renting; above 4% favours buying. A 2BHK in a good Pune suburb costs around ₹90 lakh. The same flat rents for roughly ₹25,000 a month. Buy it with an 80% loan at an assumed 8.25%, and your monthly outgo is close to ₹68,000. Rent it, and you have ₹43,000 a month spare. What you do with that ₹43,000 settles most of the rent vs buy debate. (8.25% is a cautious assumption: advertised starting home loan rates in mid-October 2026 were about 7.15% to 7.70%, and the rate actually offered depends on credit score, loan size and how fast the lender passes on the October repo hike.) This guide builds a transparent 10-year rent vs buy model for Pune, using official National Housing Bank price data, current home loan rates after the October 2026 hike, and stated assumptions you can swap for your own. It then covers tax, the break-even maths and the non-financial reasons that still matter. Is it better to rent or buy a house in Pune? The rent vs buy decision compares two paths with the same monthly budget. The buyer pays a down payment, purchase costs, EMIs and upkeep, and owns a home. The renter pays rent and invests everything the buyer would have spent extra, including the down payment. The answer turns on four numbers: rental yield (annual rent as a share of price), expected price growth, the home loan rate, and what the renter's investments earn. In Pune today, yields are low and price growth has slowed, while loan rates have just risen. That combination tilts the maths towards renting, unless you stay long and prices pick up. Pune's price-to-rent ratio Our example flat costs ₹90 lakh and rents for ₹3 lakh a year. That is a price-to-rent ratio of 30, or a gross rental yield of 3.3%. Put differently, you pay 30 years of rent upfront to own it. A gross yield in the 2–4% range is common for Indian residential property, while a home loan now costs over 8%. We could not find an official rent index for Pune, and listing-portal rents vary widely by locality and furnishing. So treat ₹25,000 as an illustration and plug in actual rents for the society you are considering. How fast are Pune property prices rising? The National Housing Bank's RESIDEX tracks housing prices in 50 cities using valuation data from lenders. Pune's index rose 6.1% in the year to June 2023, 6.4% to June 2024 and 6.0% to June 2025, before slowing to 3.5% in the year to December 2025, the latest NHB release. Over this period that works out to roughly 5.5% a year. The slowdown stands out against other cities. In the same NHB release (October–December 2025), Bengaluru's index rose 12.7% and Mumbai's 3.7% year on year, while the 50-city composite rose 5.0%. Past growth is no promise of future growth, and city averages hide wide differences between, say, Baner and Wagholi. But it is a useful anchor: our base case uses 5.5% a year, with tests at a slower 3.7% and a faster 7%. Our 10-year rent vs buy model: the assumptions Assumption Buyer Renter Flat price ₹90 lakh Same flat, rented Upfront cash ₹18 lakh down payment (20%) plus ₹6.3 lakh stamp duty, registration and costs (7%) Same ₹24.3 lakh invested on day one Loan ₹72 lakh at 8.25% floating, 20 years; EMI ₹61,349 None Running costs ₹80,000 a year for maintenance, property tax and repairs, rising 5% ₹25,000 a month rent, rising 5% a year, plus half a month's rent yearly for brokerage and agreements Monthly difference None Buyer's outgo minus rent, invested every month Returns Flat price grows 5.5% a year Portfolio earns 10% a year (tested at 8% and 12%) Exit at year 10 1% selling cost, 12.5% tax on gain 12.5% tax on gains above ₹1.25 lakh Both paths spend exactly the same cash each month, so the comparison is fair. We assume the new tax regime, which gives no deduction for a self-occupied home loan, and no HRA exemption for the renter. The old regime is discussed below. Rent vs buy in Pune: what the 10-year numbers show In year one, the buyer pays ₹61,349 in EMI plus about ₹6,700 a month in upkeep, around ₹68,000 in all. The renter pays ₹25,000 rent and invests the rest, roughly ₹43,000 a month. By year 10, rent has grown to about ₹38,800, so the monthly gap narrows to about ₹31,000. After 10 years, the flat is worth about ₹1.54 crore, and the buyer still owes about ₹50 lakh on the loan, having paid about ₹51.6 lakh in interest. After selling costs and tax, the buyer's net worth is about ₹95.2 lakh. The renter's portfolio, after tax, is about ₹1.30 crore. Line chart of rent vs buy in Pune showing net worth of buyer and renter over 10 years Scenario (10 years) Buyer net worth Renter net worth Who is ahead Base: 5.5% price growth, 10% returns ₹95.2 lakh ₹130.2 lakh Renter by ₹35 lakh Prices grow 3.7% (slow-growth test) ₹74.1 lakh ₹130.2 lakh Renter by ₹56 lakh Prices grow 7% ₹115.4 lakh ₹130.2 lakh Renter by ₹15 lakh Renter earns only 8% ₹95.2 lakh ₹114.1 lakh Renter by ₹19 lakh Renter invests only half the gap ₹95.2 lakh ₹94.2 lakh Roughly level Renter invests nothing ₹95.2 lakh ₹58.3 lakh Buyer by ₹37 lakh The last two rows are the most important in the table. Renting wins only if you actually invest the difference, month after month, for a decade. Many people do not. For them, the EMI works as forced saving, and buying comes out ahead. What if I stay longer than 10 years? The renter's lead persists in our model at longer horizons: about ₹2.24 crore vs ₹1.56 crore at 15 years and ₹3.67 crore vs ₹2.40 crore at 20 years. That is because a 3.3% yield is far below the cost of a loan, and both pots keep compounding. Once the loan is repaid the owner pays no EMI while rent keeps rising, but that only closes the gap if prices also grow faster or rents rise faster than 5% a year. Over five years the renter leads by about ₹17 lakh (₹67 lakh vs ₹51 lakh), as purchase costs have had little time to be recovered. How much must Pune prices rise for buying to win? We solved the model for the price growth at which both paths end level after 10 years. If the renter earns 8% a year, Pune homes need to appreciate about 6.9% a year. At 10% returns, the break-even is about 8.0%; at 12%, about 9.1%. Break-even property price growth needed for buying to beat renting in Pune Economists call the logic behind this the user cost of owning a home. Each year, an owner gives up interest on the loan, the return on the down payment, upkeep and depreciation. Price growth has to cover that, or renting is cheaper. With an 8.25% loan and a 3.3% yield, price growth has to do a lot of work. Rental yield vs price growth: the sensitivity table The table shows the buyer's lead (positive) or lag (negative) after 10 years in ₹ lakh, for the same ₹90 lakh flat at different rents and price growth rates, with the renter earning 10%. Gross yield (monthly rent) 3% growth 4% growth 5.5% growth 7% growth 8% growth 2.5% (₹18,750) −78 −68 −50 −30 −15 3.0% (₹22,500) −69 −59 −41 −21 −6 3.5% (₹26,250) −60 −50 −32 −12 +3 4.0% (₹30,000) −51 −41 −23 −3 +12 Higher rents help the buyer because the renter has less to invest. Even so, buying only pulls ahead in the top-right corner: yields of 3.5% or more and price growth near 8%. Does the old tax regime change the answer? Under the old regime, a buyer can deduct up to ₹2 lakh of home loan interest a year and count principal within the ₹1.5 lakh limit. In the 30% slab, the interest deduction alone saves about ₹62,400 a year; invested at 10%, that grows to about ₹10 lakh over 10 years. But the renter also gains under the old regime through HRA exemption, and Pune is now one of the cities where HRA can be exempt up to 50% of basic salary. For a salaried renter with HRA, the two benefits roughly offset each other. See our guides on home loan tax benefits (/insights/home-loan-tax-benefits-old-new-regime) and HRA exemption (/insights/hra-exemption-calculation) to check your own case. Costs the simple EMI vs rent comparison misses Putting a ₹61,000 EMI next to ₹25,000 rent leaves out much of what owning actually costs. The model above already includes the largest items; the checklist below is the fuller list for a ₹90 lakh Pune flat. Stamp duty and registration as per Maharashtra rates for Pune urban areas; GST as per current GST rates on residential property. Other amounts are indicative and vary by project and lender. Cost Typical amount on a ₹90 lakh flat Included in our model? Stamp duty (Pune urban 7%; 6% for a woman buyer) ₹6.3 lakh (₹5.4 lakh for a woman buyer) Yes Registration fee (1%, capped at ₹30,000) ₹30,000 Not separately; adds about ₹30,000 GST on an under-construction flat (5%; 1% for affordable housing; none on a ready flat with an occupancy certificate) About ₹4.5 lakh if under construction No: the model assumes a ready flat Return given up on the down payment and upfront costs ₹24.3 lakh that could otherwise compound Yes Maintenance, property tax and repairs About ₹80,000 a year to start Yes Loan processing, legal and valuation charges Varies by lender No Interiors, furniture and appliances Often several lakh for a bare flat No Home insurance A few thousand rupees a year No Rent and EMI together until possession Full rent plus pre-EMI or EMI, for an under-construction flat No Selling cost and tax at exit 1% selling cost plus 12.5% tax on the gain Yes Two items deserve a closer look. First, an under-construction flat often means paying rent and an EMI at the same time for two or three years, which can add more to the cost than any single fee. Second, TDS of 1% on purchases of ₹50 lakh or more is deducted from the payment to the seller and deposited with the government; it is not an extra cost to the buyer. Renters have costs too: brokerage, a security deposit, moving costs, and the risk of a rent increase or a forced move at the end of an agreement. That is why the model adds half a month's rent each year to the renter's side. The aim is not to show that buying is always worse, only that a fair comparison counts every rupee on both sides. When does buying make sense in Pune? Money is not the only return on a home. The security of not being asked to move, freedom to renovate, a school your children will attend for years, and the comfort of a paid-off house in retirement all have value. For many families, those outweigh a ₹20–30 lakh difference in a model. Comparison of factors favouring buying or renting a home in Pune Buying is a reasonable choice when most of these hold: You expect to live in the same area for at least 10 years. Your job and income are stable, and the EMI stays below about 40% of take-home pay. After the down payment, you still have a six-month emergency fund (/insights/emergency-fund-guide-india) . The rent for a similar flat is close to 3.5–4% of its price. You buy a ready or near-ready flat from a MahaRERA-registered project with clear title. Renting is the stronger choice if your work may take you to Bengaluru or abroad, if you are early in your career, or if you would rather keep your money liquid and diversified. A renter in Hinjewadi today may be working from Kharadi in three years. How to run the rent vs buy numbers for your own flat Get the real price: agreement value plus about 7% for stamp duty, registration and other costs; check current rates in our Maharashtra stamp duty checklist (/insights/buying-flat-maharashtra-rera-stamp-duty-checklist) . Get the real rent: ask brokers for the rent on similar flats in the same society. Get a loan quote after the October 2026 hike; our home loan guide (/insights/home-loan-guide-2026) explains eligibility and LTV limits. Compute the monthly gap between EMI plus upkeep and rent, and decide honestly whether you will invest it, for example through a SIP (/insights/sip-planning-guide-india) . Test three price growth rates , such as 4%, 6% and 8%, and see where your answer flips. If you buy, our articles on prepaying the loan vs investing (/insights/prepay-home-loan-or-invest) and on real estate vs mutual funds (/insights/real-estate-vs-mutual-funds-where-should-your-next-20-lakh-go) help with the next decisions. If you are thinking of buying a second flat to let out, read our analysis of Pune rental yields for buy-to-let (/insights/pune-rental-yields-buy-to-let) . Related reading Home loan guide 2026: eligibility, rates and process (/insights/home-loan-guide-2026) Pune rental yields: is buy-to-let worth it? (/insights/pune-rental-yields-buy-to-let) Prepay your home loan or invest? (/insights/prepay-home-loan-or-invest) Home loan tax benefits under old and new regimes (/insights/home-loan-tax-benefits-old-new-regime) Real estate vs mutual funds (/insights/real-estate-vs-mutual-funds-where-should-your-next-20-lakh-go) Frequently Asked Questions Is it better to rent or buy in Pune in 2026? Financially, renting and investing the difference usually wins in Pune when rent is around 3% of the price and home loans cost over 8%. Our 10-year model of a ₹90 lakh flat leaves the renter about ₹35 lakh ahead at 5.5% price growth. Buying makes sense if you will stay 10 years or more, prices grow faster, or you would not invest the savings. What is the rental yield in Pune? There is no official Pune rent index, so yields have to be worked out flat by flat. Divide annual rent by the price: a ₹90 lakh flat renting at ₹25,000 a month yields 3.3%. Gross residential yields in Indian cities commonly sit in the 2–4% range, before maintenance, vacancy and tax reduce them further. How much have Pune property prices increased? According to the National Housing Bank's RESIDEX, Pune's house price index rose 3.5% in the year to December 2025 (the latest release), after rises of 6.0%, 6.4% and 6.1% in the years to June 2025, 2024 and 2023. That is about 5.5% a year compounded, slower than the 5.0% rise in the 50-city index in the latest release. What property price growth is needed for buying to beat renting? In our model, with an 8.25% home loan and a 3.3% rental yield, Pune flats need to appreciate about 8% a year for buying to match a renter earning 10% on investments. If the renter earns 8%, the break-even is about 6.9%; if 12%, about 9.1%. Is a home loan EMI better than paying rent? Not automatically. In the early years most of the EMI is interest, which, like rent, builds no wealth. On a ₹72 lakh loan at 8.25%, about ₹51.6 lakh of the first 10 years of EMIs goes to interest. The EMI's advantage is forced saving through principal repayment and exposure to price growth. How long should I stay to make buying worthwhile? Stamp duty, registration and selling costs take years to recover, so buying rarely pays if you may sell within five years. In our model the renter leads at five, ten and twenty years with a 3.3% yield. The case for buying strengthens the longer you stay, the higher the rent relative to price, and the faster prices grow. Sources: National Housing Bank RESIDEX (https://residex.nhbonline.org.in/) ; NHB RESIDEX press release, October–December 2025 (https://www.nhb.org.in/wp-content/uploads/2026/03/National-Press-Release-RESIDEX-Dec25-DV002.pdf) ; NHB RESIDEX press release, January–March 2026 (https://residex.nhbonline.org.in/DataUploadFormats/PressRelease_English/Press%20Release%20January-March%202026.pdf) ; NHB RESIDEX press release, April–June 2025 (https://residex.nhbonline.org.in/DataUploadFormats/PressRelease_English/Press%20Release%20April-June%202025.pdf) ; NHB RESIDEX press release, April–June 2024 (https://residex.nhbonline.org.in/DataUploadFormats/PressRelease_English/Press%20Release%20April-June%202024.pdf) ; RBI Master Circular – Housing Finance (1 Apr 2025) (https://www.rbi.org.in/Scripts/BS_ViewMasterCirculars.aspx?Id=12824&Mode=0) ; Business Standard on lending rate increases (8 Oct 2026) (https://www.business-standard.com/amp/economy/news/state-owned-banks-raise-repo-linked-lending-rates-by-25-bps-after-rbi-move-126100801274_1.html) . The rent figure and all model results are illustrative Money n Wealth calculations. Weighing a home purchase against your other goals? The right answer depends on your job stability, savings habit and family plans, which no model can capture. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
Is it better to rent or buy in Pune in 2026?
Financially, renting and investing the difference usually wins in Pune when rent is around 3% of the price and home loans cost over 8%. Our 10-year model of a ₹90 lakh flat leaves the renter about ₹35 lakh ahead at 5.5% price growth. Buying makes sense if you will stay 10 years or more, prices grow faster, or you would not invest the savings.
What is the rental yield in Pune?
There is no official Pune rent index, so yields have to be worked out flat by flat. Divide annual rent by the price: a ₹90 lakh flat renting at ₹25,000 a month yields 3.3%. Gross residential yields in Indian cities commonly sit in the 2–4% range, before maintenance, vacancy and tax reduce them further.
How much have Pune property prices increased?
According to the National Housing Bank's RESIDEX, Pune's house price index rose 3.5% in the year to December 2025 (the latest release), after rises of 6.0%, 6.4% and 6.1% in the years to June 2025, 2024 and 2023. That is about 5.5% a year compounded, slower than the 5.0% rise in the 50-city index in the latest release.
What property price growth is needed for buying to beat renting?
In our model, with an 8.25% home loan and a 3.3% rental yield, Pune flats need to appreciate about 8% a year for buying to match a renter earning 10% on investments. If the renter earns 8%, the break-even is about 6.9%; if 12%, about 9.1%.
Is a home loan EMI better than paying rent?
Not automatically. In the early years most of the EMI is interest, which, like rent, builds no wealth. On a ₹72 lakh loan at 8.25%, about ₹51.6 lakh of the first 10 years of EMIs goes to interest. The EMI's advantage is forced saving through principal repayment and exposure to price growth.
How long should I stay to make buying worthwhile?
Stamp duty, registration and selling costs take years to recover, so buying rarely pays if you may sell within five years. In our model the renter leads at five, ten and twenty years with a 3.3% yield. The case for buying strengthens the longer you stay, the higher the rent relative to price, and the faster prices grow.
Weighing a home purchase against your other goals?
The right answer depends on your job stability, savings habit and family plans, which no model can capture. Talk to Money n Wealth for a free portfolio review.