EMI Calculator Guide 2026: How to Cut the Total Interest on Any Loan
Last updated: 13 October 2026
Quick answer: An EMI calculator uses the formula EMI = P × r × (1+r)n ÷ [(1+r)n − 1] to split a loan into equal monthly payments. Early EMIs are mostly interest, so total interest is driven by tenure and rate. To cut it, choose the shortest affordable tenure, prepay early, raise your EMI when income rises, and compare loans on APR, never on a flat rate.
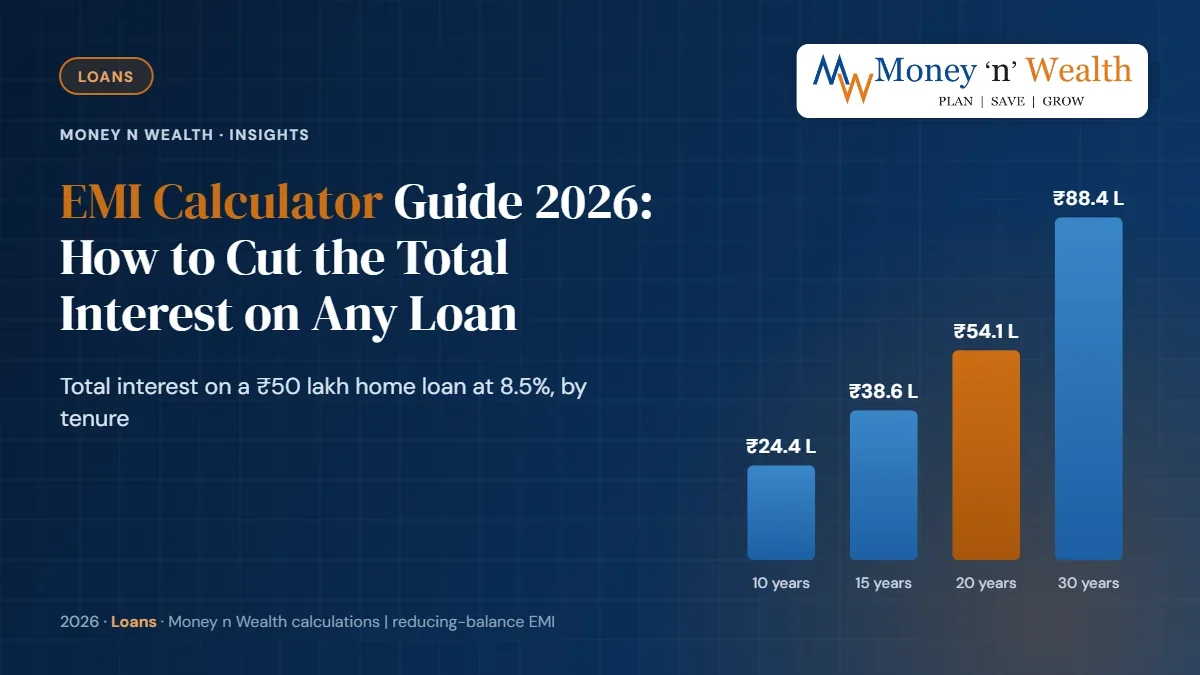
Last updated: 13 October 2026 Quick answer: An EMI calculator uses the formula EMI = P × r × (1+r) n ÷ [(1+r) n − 1] to split a loan into equal monthly payments. Early EMIs are mostly interest, so total interest is driven by tenure and rate. To cut it, choose the shortest affordable tenure, prepay early, raise your EMI when income rises, and compare loans on APR, never on a flat rate. Key takeaways Front-loaded: on a ₹50 lakh, 20-year loan at 8.5%, 82% of the first EMI is interest. Tenure trap: stretching from 20 to 30 years saves ₹4,945 a month but adds ₹34.3 lakh of interest. Prepay early: ₹1 lakh prepaid in year 1 saves ₹3.8 lakh; the same in year 15 saves ₹51,000. Small habits win: ₹5,000 extra a month saves ₹13.9 lakh and ends the loan 4.4 years early. Flat-rate trap: a "10% flat" loan over five years really costs about 17.3% a year. Most borrowers look at one number before signing a loan: the EMI. Lenders know this, which is why a longer tenure is the easiest product to sell. Yet on a typical home loan, the interest you pay over the life of the loan can exceed the amount you borrowed. A ₹50 lakh home loan at 8.5% for 20 years has an EMI of ₹43,391. Over 240 months you pay ₹1.04 crore, of which ₹54.1 lakh is interest. With the RBI raising the repo rate to 5.50% on 7 October 2026, floating rates are moving up, and that bill is set to grow. This guide explains how an EMI calculator works, why your early EMIs barely dent the principal, and the specific levers that cut total interest on a home, car or personal loan. All figures are Money n Wealth calculations on a reducing-balance basis. What is an EMI and how does an EMI calculator work? An EMI (Equated Monthly Instalment) is the fixed monthly payment that repays a loan's interest and principal over an agreed tenure. Each EMI first pays the month's interest on the outstanding balance; the rest reduces the principal. An EMI calculator simply solves for the payment that brings the balance to zero on the last month. The EMI formula EMI = P × r × (1 + r) n ÷ [(1 + r) n − 1], where P is the loan amount, r is the monthly interest rate (annual rate ÷ 12 ÷ 100) and n is the number of months. For ₹50 lakh at 8.5% for 20 years: r = 0.0070833 and n = 240, which gives ₹43,391. In Excel or Google Sheets, =PMT(8.5%/12, 240, -5000000) returns the same figure. You can also use the Money n Wealth EMI calculator (/tools) . Worked EMIs for common loans Loan Amount Rate (reducing) Tenure EMI Total interest Home loan ₹50 lakh 8.5% 20 years ₹43,391 ₹54.14 lakh Car loan ₹8 lakh 9% 5 years ₹16,607 ₹1.96 lakh Personal loan ₹5 lakh 12% 3 years ₹16,607 ₹97,858 Personal loan ₹5 lakh 14% 5 years ₹11,634 ₹1.98 lakh Notice the last two rows. Stretching a personal loan from three to five years cuts the EMI by about ₹5,000 but doubles the interest. That pattern holds for every loan. Why are early EMIs mostly interest? Understanding amortisation An amortisation schedule is the month-by-month table showing how each EMI splits between interest and principal. Because interest is charged on the outstanding balance, it is largest at the start, when you owe the most. In month one of our ₹50 lakh loan, interest is ₹35,417 of the ₹43,391 EMI, or about 82%. Only ₹7,974 reduces the loan. After five years you will have paid ₹26 lakh in EMIs, yet the balance falls only to ₹44.1 lakh. Half the principal is cleared only in month 166, nearly 14 years in. EMI calculator amortisation chart showing interest falling and principal rising over a 20-year home loan End of year Interest paid that year Principal repaid that year Balance left 1 ₹4.21 lakh ₹1.00 lakh ₹49.0 lakh 5 ₹3.81 lakh ₹1.40 lakh ₹44.1 lakh 10 ₹3.07 lakh ₹2.13 lakh ₹35.0 lakh 15 ₹1.95 lakh ₹3.26 lakh ₹21.1 lakh 20 ₹0.23 lakh ₹4.97 lakh Nil This has two practical consequences. First, any extra payment in the early years saves far more interest than the same payment later. Second, if you sell the house or switch lenders after a few years, you will find you still owe most of what you borrowed. Since 1 October 2024, RBI's Key Facts Statement rules require banks and NBFCs to give retail borrowers a KFS with the full repayment schedule and the all-in APR before signing. Ask for it and read it. How does loan tenure change the total interest? Tenure is the most powerful lever, and the one borrowers misjudge most. A longer tenure lowers the EMI only slightly while raising total interest sharply. Total interest on a home loan by tenure from an EMI calculator Moving from 20 to 30 years reduces the EMI by ₹4,945 a month, about 11%. Total interest rises from ₹54.1 lakh to ₹88.4 lakh. Moving from 20 to 15 years costs ₹5,846 more a month but saves ₹15.5 lakh. Does a 0.5% rate difference matter? Yes, more than most people expect. On ₹50 lakh for 20 years, each 0.5% adds roughly ₹1,600 to the EMI and ₹3.8 lakh to total interest. Interest rate EMI Total interest (20 years) 8.0% ₹41,822 ₹50.37 lakh 8.5% ₹43,391 ₹54.14 lakh 9.0% ₹44,986 ₹57.97 lakh 9.5% ₹46,607 ₹61.86 lakh When the RBI raises rates, banks usually extend the tenure of a floating-rate loan rather than raising the EMI, which quietly adds to total interest. RBI's August 2023 circular on floating-rate resets lets you choose a higher EMI, a longer tenure or a mix, and to switch to a fixed rate. Our guide on raising the EMI or extending the tenure after the hike (/insights/home-loan-emi-vs-tenure-after-rate-hike) works through that choice. How much interest does prepaying a loan save? Prepayment works because every rupee of extra principal stops attracting interest for the rest of the loan. Keeping the EMI unchanged and letting the tenure shrink saves the most. Home loan prepayment savings compared using an EMI calculator Prepayment habit (₹50 lakh, 8.5%, 20 years) Loan ends in Interest saved ₹1 lakh at the end of every year 14 years ₹18.55 lakh ₹5,000 extra every month 15 years 7 months ₹13.89 lakh EMI raised by 10% (₹4,339) 16 years ₹12.52 lakh One extra EMI a year (₹43,391) 16 years 9 months ₹10.29 lakh ₹5 lakh once, after year 5 17 years ₹10.69 lakh Timing matters more than amount A single ₹1 lakh prepayment saves about ₹3.82 lakh of interest if made at the end of year 1, ₹2.48 lakh in year 5, ₹1.30 lakh in year 10 and only ₹51,000 in year 15. The earlier, the better. Reduce the EMI or the tenure? After a prepayment, lenders usually offer both. On a ₹5 lakh prepayment after year 5, cutting the tenure saves ₹10.69 lakh of interest. Cutting the EMI instead (to ₹38,467) saves only ₹3.86 lakh. Choose a lower EMI only if your cash flow needs relief. Are there prepayment charges? For floating-rate loans taken by individuals for non-business purposes, no. RBI's Pre-payment Charges on Loans Directions, 2025 bar such charges on loans sanctioned or renewed on or after 1 January 2026, regardless of the source of funds and with no lock-in. Fixed-rate loans, including most car and personal loans, can carry foreclosure charges under the lender's policy, so check the sanction letter and KFS. Whether prepaying beats investing depends on your post-tax loan cost and expected returns. See prepay your home loan or invest (/insights/prepay-home-loan-or-invest) for the full comparison. Never prepay with your emergency fund (/insights/emergency-fund-guide-india) . What is the flat rate trap, and how do you spot it? A flat interest rate charges interest on the original loan amount for the whole tenure, even as you repay. A reducing-balance rate charges interest only on what you still owe. The same quoted number therefore means very different costs. Flat interest rate versus reducing balance rate comparison for EMI loans Quoted flat rate Tenure Equivalent reducing-balance rate 5% 5 years about 9.2% 6% 3 years about 11.1% 7% 5 years about 12.5% 10% 3 years about 17.9% 10% 5 years about 17.3% 12% 2 years about 21.6% As a rough rule, the true rate is a little under double the flat rate. Flat rates still appear in some dealer-arranged two-wheeler and car finance, consumer durable loans and informal lending. The fix is simple: ask for the APR in the Key Facts Statement. RBI requires lenders to disclose an all-inclusive APR covering fees, so you can compare offers on one number. The same logic applies to "no-cost EMI" offers. RBI's card rules say interest-bearing EMIs must not be marketed as zero-cost, and the discount offsetting the interest must be shown separately. Our guide to credit card debt (/insights/credit-card-debt-minimum-due-trap) covers card EMIs in detail. How to use an EMI calculator before you borrow Steps to use an EMI calculator when comparing loans Use the APR, not the headline rate. Processing fees, insurance and other charges raise the real cost. Run three tenures. Note the EMI and total interest for each. Check affordability. Lenders set their own limits on how much of your income can go to EMIs. For comfort, keep all EMIs within about 35–40% of take-home pay. Stress-test floating rates. Add 1% and make sure you could still pay. Rates rose 2.5% in 2022–23 and are rising again. Build in prepayment. Pick the tenure you can afford comfortably, then prepay from bonuses and pay rises. What do borrowers in other countries do differently? Global practice offers useful lessons. In the US, the CARD Act requires card statements to show how long repayment takes on minimum payments, and most US mortgages are 30-year fixed-rate loans. That gives payment certainty but more total interest, which is why many Americans refinance when rates fall. In the UK and Canada, fixed rates usually last two to five years before resetting. Borrowers are used to planning around each reset. Indian floating-rate borrowers face resets at least quarterly on repo-linked loans, so checking your rate and tenure after every RBI policy matters even more. Seven ways to cut the total interest on any loan Borrow less. A bigger down payment cuts interest in proportion. Pick the shortest affordable tenure. You can always prepay; you cannot easily shorten a loan you cannot afford. Improve your credit score before applying. Better scores get lower spreads. SBI, for instance, prices new car loans by credit score. Prepay early and regularly. Even ₹5,000 a month helps. Raise the EMI with each pay rise. A 10% higher EMI cuts four years off a 20-year home loan. Renegotiate or refinance. A 0.5% lower rate is worth lakhs. See home loan balance transfer (/insights/home-loan-balance-transfer) . Clear costly debt first. Repay credit cards and personal loans before prepaying a home loan, using the debt management (/insights/debt-management-guide-india) avalanche method. Related reading Prepay your home loan or invest the money? (/insights/prepay-home-loan-or-invest) After the rate hike: raise the EMI or extend the tenure? (/insights/home-loan-emi-vs-tenure-after-rate-hike) Car loan or pay cash? (/insights/car-loan-or-pay-cash) Credit card debt and the minimum-due trap (/insights/credit-card-debt-minimum-due-trap) Home loan tax benefits under old and new regimes (/insights/home-loan-tax-benefits-old-new-regime) RBI hikes repo rate to 5.50%: impact on EMIs (/insights/rbi-repo-rate-hike-october-2026-emi-fd-debt-funds) Frequently Asked Questions What is the formula used in an EMI calculator? EMI = P × r × (1+r) n ÷ [(1+r) n − 1], where P is the principal, r is the monthly rate (annual rate ÷ 1,200) and n is the tenure in months. For ₹10 lakh at 9% for 5 years, the EMI is ₹20,758. Excel's PMT function gives the same answer. Is it better to choose a lower EMI or a shorter tenure? A shorter tenure almost always costs less overall. On ₹50 lakh at 8.5%, a 15-year loan costs ₹15.5 lakh less interest than a 20-year loan, for ₹5,846 more a month. Choose the shortest tenure whose EMI stays comfortably within about 35–40% of take-home pay, and keep an emergency fund. Should I reduce my EMI or tenure after a home loan prepayment? Reduce the tenure if you can manage the existing EMI. In our example, a ₹5 lakh prepayment after five years saves ₹10.7 lakh when the tenure shortens, but only ₹3.9 lakh when the EMI is lowered. A lower EMI makes sense only when monthly cash flow is tight. Are there charges for prepaying a home loan? Not on floating-rate loans to individuals for non-business purposes. RBI's 2025 prepayment directions, applying to loans sanctioned or renewed from 1 January 2026, bar such charges and any lock-in. Fixed-rate loans may carry a foreclosure fee under the lender's policy, which must be disclosed in the sanction letter and Key Facts Statement. How do I convert a flat interest rate into a reducing rate? Compute the EMI the flat rate implies: (principal + principal × flat rate × years) ÷ months. Then find the reducing-balance rate that produces the same EMI, using Excel's RATE function. A 10% flat rate over five years works out to about 17.3%. The lender's KFS APR does this for you. Why does my outstanding balance fall so slowly? Because interest is charged on the balance, early EMIs are mostly interest. On a 20-year loan at 8.5%, only about 18% of the first EMI repays principal, and half the loan is repaid only after about 14 years. Prepaying in the early years speeds this up most. Does an EMI calculator include processing fees and insurance? Most basic calculators do not. They use the interest rate alone. Fees, bundled insurance and other charges raise the effective cost, which is why RBI requires lenders to disclose an all-inclusive APR in the Key Facts Statement. Use that APR in the calculator for a truer comparison. Sources: RBI, Key Facts Statement for Loans and Advances (15 Apr 2024) (https://rbi.org.in/Scripts/NotificationUser.aspx?Id=12663&Mode=0) ; RBI, Reset of Floating Interest Rate on EMI-based Personal Loans (18 Aug 2023) (https://rbi.org.in/Scripts/BS_CircularIndexDisplay.aspx?Id=12529) ; SCC Online on RBI Pre-payment Charges on Loans Directions 2025 (https://www.scconline.com/blog/post/2025/07/10/rbi-prepayment-charges-on-loans-directions-2025/) ; RBI Master Direction on Credit and Debit Cards (updated 7 Mar 2024) (https://rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=12300) ; SBI auto loan interest rates (https://sbi.bank.in/web/interest-rates/interest-rates/loan-schemes-interest-rates/auto-loans) ; CFPB, Regulation Z §1026.7 (minimum payment disclosures) (https://www.consumerfinance.gov/rules-policy/regulations/1026/7/) . Worked examples are Money n Wealth calculations. Wondering how fast you could close your loan? A personalised prepayment plan weighs your loans, tax position, emergency fund and investment goals together. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
What is the formula used in an EMI calculator?
EMI = P × r × (1+r) n ÷ [(1+r) n − 1], where P is the principal, r is the monthly rate (annual rate ÷ 1,200) and n is the tenure in months. For ₹10 lakh at 9% for 5 years, the EMI is ₹20,758. Excel's PMT function gives the same answer.
Is it better to choose a lower EMI or a shorter tenure?
A shorter tenure almost always costs less overall. On ₹50 lakh at 8.5%, a 15-year loan costs ₹15.5 lakh less interest than a 20-year loan, for ₹5,846 more a month. Choose the shortest tenure whose EMI stays comfortably within about 35–40% of take-home pay, and keep an emergency fund.
Should I reduce my EMI or tenure after a home loan prepayment?
Reduce the tenure if you can manage the existing EMI. In our example, a ₹5 lakh prepayment after five years saves ₹10.7 lakh when the tenure shortens, but only ₹3.9 lakh when the EMI is lowered. A lower EMI makes sense only when monthly cash flow is tight.
Are there charges for prepaying a home loan?
Not on floating-rate loans to individuals for non-business purposes. RBI's 2025 prepayment directions, applying to loans sanctioned or renewed from 1 January 2026, bar such charges and any lock-in. Fixed-rate loans may carry a foreclosure fee under the lender's policy, which must be disclosed in the sanction letter and Key Facts Statement.
How do I convert a flat interest rate into a reducing rate?
Compute the EMI the flat rate implies: (principal + principal × flat rate × years) ÷ months. Then find the reducing-balance rate that produces the same EMI, using Excel's RATE function. A 10% flat rate over five years works out to about 17.3%. The lender's KFS APR does this for you.
Why does my outstanding balance fall so slowly?
Because interest is charged on the balance, early EMIs are mostly interest. On a 20-year loan at 8.5%, only about 18% of the first EMI repays principal, and half the loan is repaid only after about 14 years. Prepaying in the early years speeds this up most.
Does an EMI calculator include processing fees and insurance?
Most basic calculators do not. They use the interest rate alone. Fees, bundled insurance and other charges raise the effective cost, which is why RBI requires lenders to disclose an all-inclusive APR in the Key Facts Statement. Use that APR in the calculator for a truer comparison.
Wondering how fast you could close your loan?
A personalised prepayment plan weighs your loans, tax position, emergency fund and investment goals together. Talk to Money n Wealth for a free portfolio review.