Home Loan Balance Transfer in 2026: When Switching Lenders Pays
Last updated: 13 October 2026
Quick answer: A home loan balance transfer means moving your outstanding loan to another lender at a lower rate. It usually pays when the rate gap is at least 0.50%, more than about 10 years remain, and the balance is ₹25 lakh or more. Below that, switching costs eat most of the saving. Always ask your current lender to match the rate first.
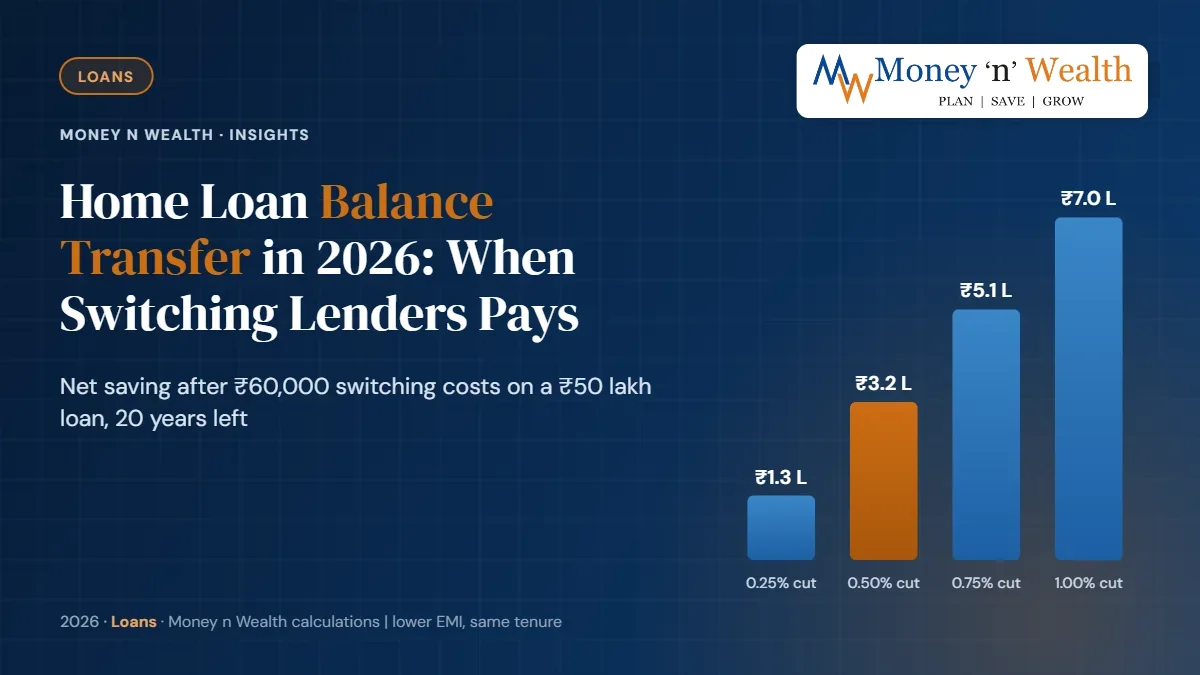
Last updated: 13 October 2026 Quick answer: A home loan balance transfer means moving your outstanding loan to another lender at a lower rate. It usually pays when the rate gap is at least 0.50%, more than about 10 years remain, and the balance is ₹25 lakh or more. Below that, switching costs eat most of the saving. Always ask your current lender to match the rate first. Key takeaways Example: 0.50% off a ₹50 lakh, 20-year loan cuts the EMI by ₹1,587 and saves about ₹3.2 lakh after ₹60,000 costs. Break-even: costs are usually recovered in about 38 months at a 0.50% gap, 19 months at 1%. Late is costly: with five years left, a 0.50% cut nets only about ₹12,000. No exit fee: RBI rules bar foreclosure charges on floating-rate loans to individuals. Negotiate first: since 1 October 2025, banks may cut spreads early to retain borrowers. Rate hikes make borrowers look at their loans; rate gaps make them move. After the RBI raised the repo rate to 5.50% on 7 October 2026, repo-linked lending rates at banks such as Punjab National Bank and Indian Bank rose to 8.35% and 8.20%. Yet many borrowers on older loans are paying well above the rates offered to new customers with similar credit scores. A balance transfer can close that gap. This guide shows when it genuinely saves money, what it costs, how to negotiate with your existing lender first, and the process step by step, with worked numbers. What is a home loan balance transfer? A home loan balance transfer is the refinancing of your outstanding home loan by a new lender, which pays off your existing lender and takes over the mortgage on your property at its own interest rate and terms. Your house, the outstanding principal and usually the remaining tenure stay the same; the lender and the rate change. Borrowers switch for three main reasons: a lower interest rate, better service, or a top-up loan the existing lender will not provide. The rate is the one that matters most, and the only one this guide assumes. When does a home loan balance transfer pay? Three variables decide it: the rate gap, the years left, and the outstanding amount. Switching costs are largely fixed, while savings grow with all three. Take a ₹50 lakh balance at 8.85%, with ₹60,000 of total switching costs. The table shows the monthly EMI saving, the net saving over the remaining tenure and the months needed to recover the costs: Years left 0.25% lower 0.50% lower 0.75% lower 1.00% lower 20 ₹797/mo; net ₹1.31 lakh; 75 months ₹1,587/mo; net ₹3.21 lakh; 38 months ₹2,371/mo; net ₹5.09 lakh; 25 months ₹3,149/mo; net ₹6.96 lakh; 19 months 15 ₹738/mo; net ₹73,000; 81 months ₹1,470/mo; net ₹2.05 lakh; 41 months ₹2,196/mo; net ₹3.35 lakh; 27 months ₹2,918/mo; net ₹4.65 lakh; 21 months 10 ₹672/mo; net ₹21,000; 89 months ₹1,340/mo; net ₹1.01 lakh; 45 months ₹2,004/mo; net ₹1.81 lakh; 30 months ₹2,664/mo; net ₹2.60 lakh; 23 months 5 ₹604/mo; loss ₹24,000 ₹1,207/mo; net ₹12,000; 50 months ₹1,807/mo; net ₹48,000; 33 months ₹2,405/mo; net ₹84,000; 25 months Savings here assume you take the lower EMI and keep the tenure. Net figures are undiscounted. If you keep paying your old EMI instead, savings grow: at a 0.50% cut from 8.85% to 8.35% with 15 years left, keeping the old EMI clears the loan in 169 months rather than 180 and saves about ₹6 lakh in interest before costs. Home loan balance transfer net saving by remaining tenure A practical rule of thumb Worth pursuing: gap of 0.50% or more, at least 10 years left, balance above ₹25 lakh, and costs recovered within about three years. Borderline: gap of 0.25–0.50%, or under 10 years left. Negotiate with your bank instead. Rarely worth it: gap under 0.25%, or under five years left, unless costs are close to nil. Also factor in how long you will keep the loan. If you plan to prepay heavily or sell within three years, the break-even may never arrive. See prepay or invest (/insights/prepay-home-loan-or-invest) if prepayment is on your mind. How much does a balance transfer cost? Typical costs of a home loan balance transfer in India Expect to pay the new lender's processing fee, often 0.25–1% of the loan plus GST, though banks frequently waive or cap it during promotions. Add legal and technical valuation fees, CERSAI registration and stamp duty on the new mortgage, which varies by state; in Maharashtra, check the current charge for a mortgage by deposit of title deeds with your lender. Some lenders bundle a home loan insurance policy, which is optional and can add a large sum to the loan. Leaving your current lender should cost nothing extra. Under RBI rules, regulated lenders cannot levy foreclosure charges on floating-rate loans to individuals for non-business purposes, and the RBI's Pre-payment Charges on Loans Directions, 2025 reinforce this for loans sanctioned or renewed from 1 January 2026, regardless of where the money comes from. Fixed-rate or hybrid loans may still carry a charge, so check your agreement. Should you negotiate with your current lender first? Yes, always. Many banks offer existing borrowers a lower rate, for a fee, rather than lose them. Two RBI rules strengthen your hand: Switch to the external benchmark. RBI's circular of 4 September 2019 requires new floating-rate retail loans to be linked to an external benchmark and lets existing MCLR or base-rate borrowers who can prepay without charges switch, paying only reasonable administrative or legal costs. The new rate matches what a comparable new loan would get. Spread cuts for retention. From 1 October 2025, amended RBI Interest Rate on Advances directions allow banks to reduce spread components other than credit risk premium earlier than three years, for customer retention, on a non-discriminatory basis. In plain terms, your bank is now permitted to cut your spread if you threaten to leave. Comparison of renegotiation, internal conversion and home loan balance transfer Ask for the rate in writing. If the internal offer is within 0.10–0.15% of the best outside offer, the convenience and lower cost of staying usually win. Our guide on handling the October 2026 rate reset (/insights/home-loan-emi-vs-tenure-after-rate-hike) explains how EBLR and MCLR loans differ. How do you transfer a home loan, step by step? Step by step home loan balance transfer process in India Check your profile. Pull your credit report. Lenders price balance transfers by credit score, so the advertised floor rate may not be what you get. Our credit score guide (/insights/credit-score-cibil-check-improve) explains how to improve yours. Compare offers. Get sanction-level quotes from two or three lenders, including spread, benchmark, all fees and whether the rate is repo-linked. Request a foreclosure letter and list of documents from your current lender. Get the new sanction and sign the loan agreement. The new lender pays the old one directly. Collect original documents. Under RBI's circular of 13 September 2023, your old lender must release original property documents and remove charges within 30 days of full repayment, or pay ₹5,000 for each day of delay attributable to it. Hand over documents to the new lender, set up the new EMI mandate and cancel the old one. Most transfers take two to four weeks. Keep paying the old EMI until the old loan is confirmed closed, to avoid a missed payment on your credit report. Should you take a top-up loan with the transfer? New lenders often offer a top-up loan with a balance transfer. It is usually cheaper than a personal loan, but it is still debt secured on your home and it extends your borrowing. Use it for genuine needs such as home improvement or education, not consumption. The tax treatment is narrow. Interest on a top-up is deductible under section 22 of the Income-tax Act, 2025 only if the money is used to buy, build, repair or reconstruct the house, and only in the old regime for a self-occupied home. Our home loan tax benefits guide (/insights/home-loan-tax-benefits-old-new-regime) explains the rules, and for other secured options, compare personal loans, loans against mutual funds and gold loans (/insights/personal-loan-vs-lamf-vs-gold-loan) . What can go wrong with a balance transfer? Teaser rates: an attractive rate that rises after a year or two. Insist on a repo-linked rate with a fixed spread. Bundled insurance: a single-premium policy added to the loan increases your EMI. Insurance is not a condition for the loan; buy term cover separately if you need it. See how much term cover you need (/insights/term-insurance-advisor-pune) . Tenure reset: some lenders extend the tenure to the maximum to show a lower EMI. Keep the remaining tenure the same or shorter. Housing finance company pricing: HFCs price off their own prime lending rates rather than the repo rate, so passing on cuts can lag. Understand the benchmark before you sign. Rate cycle timing: if rates rise further, as SBI Research expects for December, every repo-linked loan rises equally. A transfer cuts your spread, not your exposure to the cycle. How does refinancing work elsewhere? In the United States, refinancing a fixed-rate mortgage is common when rates fall, but closing costs of a few per cent of the loan mean borrowers often need a sizeable rate drop to benefit. In the United Kingdom, most borrowers "remortgage" every two to five years when a fixed deal ends, to avoid reverting to a lender's standard variable rate. India's version is cheaper, because there is no exit penalty on floating loans, and the main prize is the spread rather than the rate cycle. Related reading After the hike: raise the EMI or extend the tenure? (/insights/home-loan-emi-vs-tenure-after-rate-hike) RBI hikes repo rate to 5.50% (/insights/rbi-repo-rate-hike-october-2026-emi-fd-debt-funds) Home loan guide 2026: eligibility and rates (/insights/home-loan-guide-2026) EMI calculator guide (/insights/emi-calculator-guide-reduce-loan-interest) Prepay your home loan or invest? (/insights/prepay-home-loan-or-invest) Loans at Money n Wealth (/products/loans) Frequently Asked Questions What is the minimum rate difference for a home loan balance transfer? As a rule of thumb, about 0.50% with at least 10 years left and a balance above ₹25 lakh. On a ₹50 lakh, 20-year loan, a 0.50% cut saves about ₹1,587 a month and recovers ₹60,000 of costs in around 38 months. Smaller gaps are better handled by negotiating with your lender. Are there foreclosure charges when transferring a home loan? Not on a floating-rate home loan taken by an individual for non-business purposes. RBI rules prohibit banks, NBFCs and housing finance companies from levying foreclosure or prepayment charges on such loans. Fixed-rate loans and the fixed portion of hybrid loans may still carry a charge, so check your agreement. Does a home loan balance transfer affect my CIBIL score? Briefly and slightly. Applications create hard enquiries, and a new account appears on your report, but closing the old loan in good standing is recorded positively. Limit applications to two or three lenders, and keep paying EMIs until the old loan is closed. Can I transfer my home loan to another bank more than once? Yes. There is no legal limit, but each transfer has costs and lenders may hesitate if you switch very often. Many borrowers transfer once early in the loan and later use the threat of a transfer to negotiate lower spreads with their existing lender. Can I switch from MCLR to repo-linked rate without a balance transfer? Usually yes. RBI's 2019 rules allow existing floating-rate borrowers to move to the external benchmark at the rate a comparable new loan would get, paying only reasonable administrative or legal costs. Ask your bank for its conversion fee and the resulting rate before considering a transfer. How long does a home loan balance transfer take? Typically two to four weeks, depending on the new lender's legal and valuation checks and how quickly your existing lender issues the foreclosure letter. After closure, the old lender must release original property documents within 30 days or pay ₹5,000 per day of delay attributable to it. Can I claim tax benefits after a balance transfer? Yes. Interest on a new loan taken to repay the original home loan remains deductible under section 22 of the Income-tax Act, 2025, and the lender's certificate should show it. Self-occupied benefits apply only in the old regime, up to ₹2 lakh of interest a year. Sources: RBI, External Benchmark Based Lending (4 Sep 2019) (https://rbi.org.in/Scripts/NotificationUser.aspx?Id=11677) ; RBI Interest Rate on Advances Amendment Directions 2025 (https://rbi.org.in/Scripts/BS_CircularIndexDisplay.aspx?Id=12541) ; RBI, release of property documents (13 Sep 2023) (https://rbi.org.in/Scripts/NotificationUser.aspx?Id=12535&Mode=0) ; SCC Online on RBI Pre-payment Charges Directions 2025 (https://www.scconline.com/blog/post/2025/07/10/rbi-prepayment-charges-on-loans-directions-2025/) ; Free Press Journal on October 2026 rate changes (https://www.freepressjournal.in/business/your-home-loan-emi-may-rise-from-october-8-these-6-banks-have-increased-lending-rates-after-rbis-big-move) ; Income Tax Department, section 22 (https://www.incometaxindia.gov.in/w/section-22-218) . Worked examples are Money n Wealth calculations; costs are illustrative. Is your home loan rate higher than it should be? A quick review of your spread, benchmark and remaining tenure shows whether to negotiate, convert or switch. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
What is the minimum rate difference for a home loan balance transfer?
As a rule of thumb, about 0.50% with at least 10 years left and a balance above ₹25 lakh. On a ₹50 lakh, 20-year loan, a 0.50% cut saves about ₹1,587 a month and recovers ₹60,000 of costs in around 38 months. Smaller gaps are better handled by negotiating with your lender.
Are there foreclosure charges when transferring a home loan?
Not on a floating-rate home loan taken by an individual for non-business purposes. RBI rules prohibit banks, NBFCs and housing finance companies from levying foreclosure or prepayment charges on such loans. Fixed-rate loans and the fixed portion of hybrid loans may still carry a charge, so check your agreement.
Does a home loan balance transfer affect my CIBIL score?
Briefly and slightly. Applications create hard enquiries, and a new account appears on your report, but closing the old loan in good standing is recorded positively. Limit applications to two or three lenders, and keep paying EMIs until the old loan is closed.
Can I transfer my home loan to another bank more than once?
Yes. There is no legal limit, but each transfer has costs and lenders may hesitate if you switch very often. Many borrowers transfer once early in the loan and later use the threat of a transfer to negotiate lower spreads with their existing lender.
Can I switch from MCLR to repo-linked rate without a balance transfer?
Usually yes. RBI's 2019 rules allow existing floating-rate borrowers to move to the external benchmark at the rate a comparable new loan would get, paying only reasonable administrative or legal costs. Ask your bank for its conversion fee and the resulting rate before considering a transfer.
How long does a home loan balance transfer take?
Typically two to four weeks, depending on the new lender's legal and valuation checks and how quickly your existing lender issues the foreclosure letter. After closure, the old lender must release original property documents within 30 days or pay ₹5,000 per day of delay attributable to it.
Can I claim tax benefits after a balance transfer?
Yes. Interest on a new loan taken to repay the original home loan remains deductible under section 22 of the Income-tax Act, 2025, and the lender's certificate should show it. Self-occupied benefits apply only in the old regime, up to ₹2 lakh of interest a year.
Is your home loan rate higher than it should be?
A quick review of your spread, benchmark and remaining tenure shows whether to negotiate, convert or switch. Talk to Money n Wealth for a free portfolio review.