Sukanya Samriddhi vs Mutual Funds for a Daughter’s Education: How to Use Both Without Choosing the Wrong Tool
Sukanya Samriddhi Yojana and mutual funds solve different problems. SSY is a government-backed small-savings scheme for an eligible girl child with defined contribution and withdrawal rules. Mutual funds are market-linked investments whose risk, return and liquidity depend on the scheme category.
The right comparison begins with the child's age, years to the goal, required corpus and family's need for flexibility.
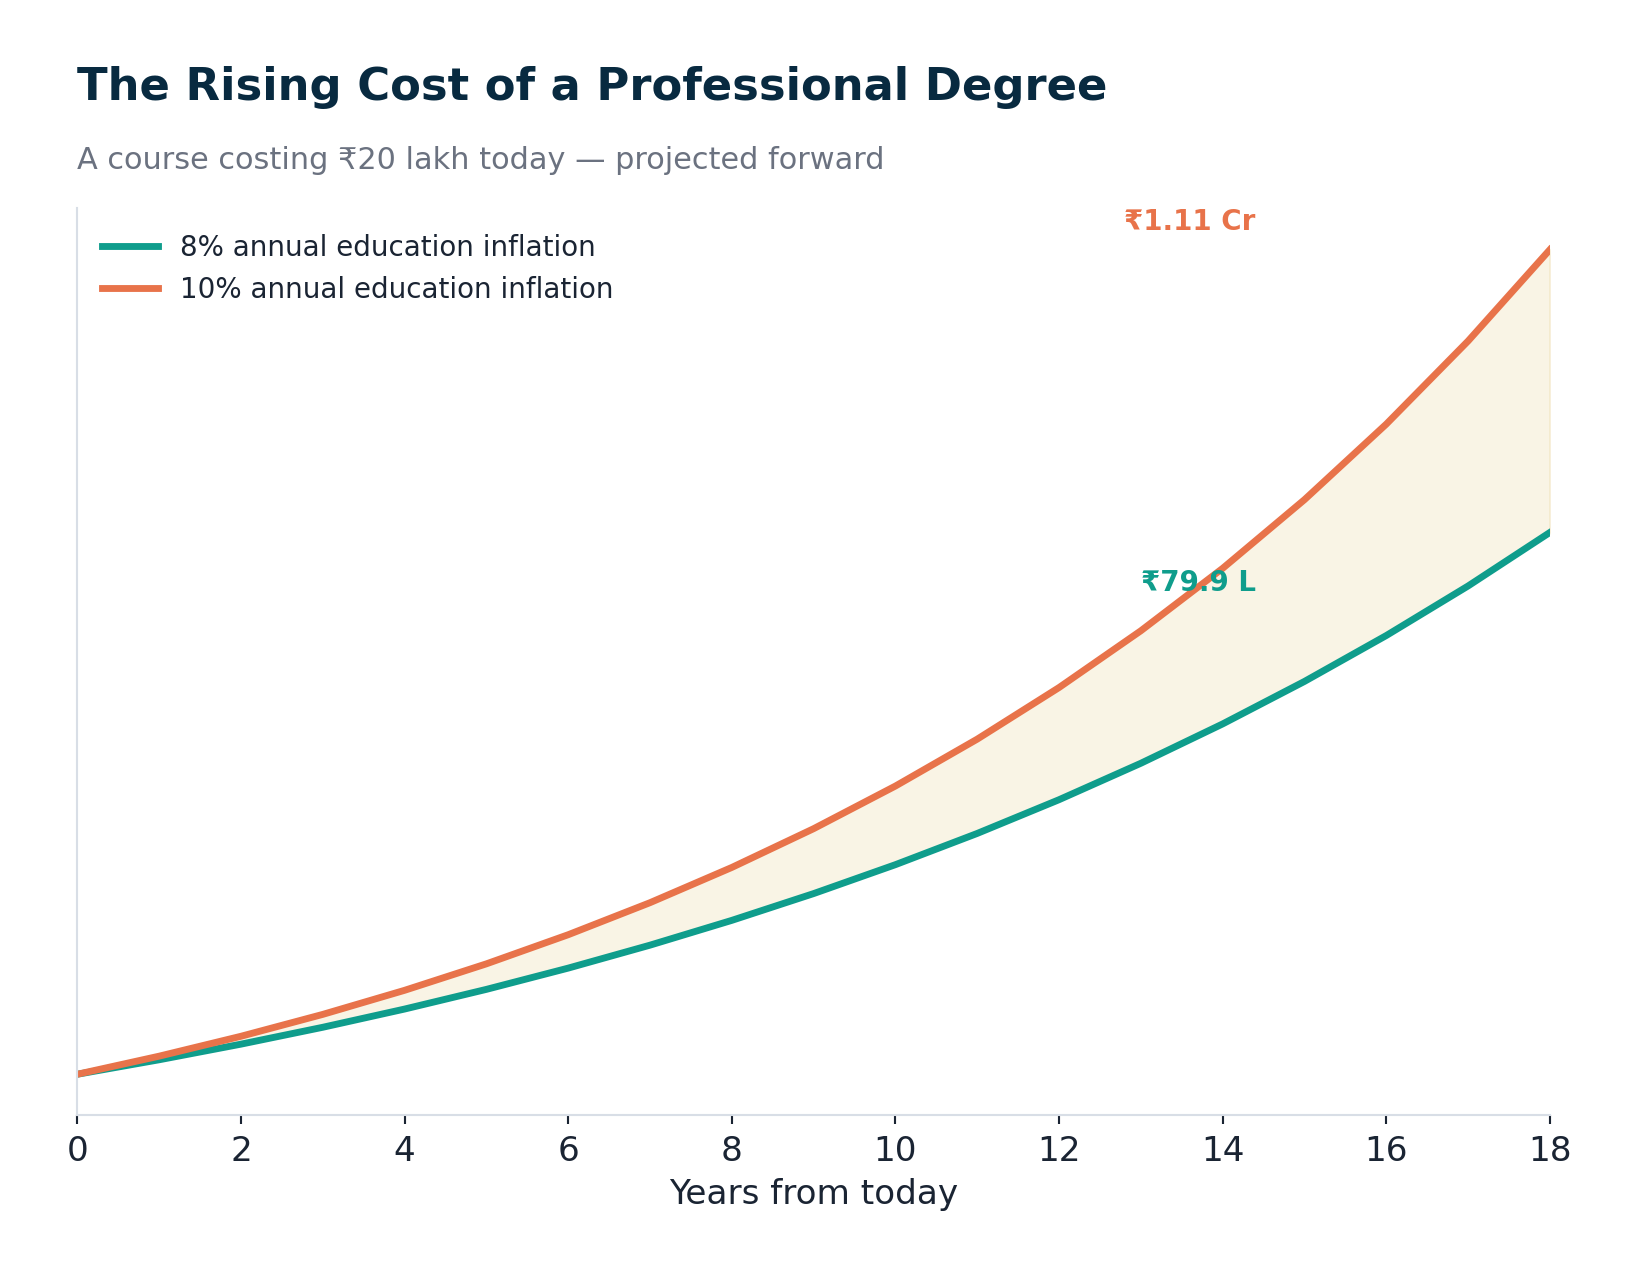
Important: Tax, FEMA, small-savings and cross-border rules can change. Figures and eligibility rules should be rechecked against current official provisions at publication and transaction time. This is not a simple return comparison Sukanya Samriddhi Yojana and mutual funds solve different problems. SSY is a government-backed small-savings scheme for an eligible girl child with defined contribution and withdrawal rules. Mutual funds are market-linked investments whose risk, return and liquidity depend on the scheme category. The right comparison begins with the child's age, years to the goal, required corpus and family's need for flexibility. Where SSY is strong SSY offers sovereign-backed saving, a rate notified by the government from time to time and tax advantages subject to prevailing law. Its restrictions can also create useful discipline because the money is not designed for casual withdrawal. For parents who value certainty of structure and are eligible to open the account, it can form a stable component of the education portfolio. Where SSY is less flexible Education costs do not always arrive exactly when a small-savings scheme matures. Admission deposits, coaching, entrance preparation or overseas applications can arise earlier. Withdrawal and account rules therefore need to be matched to the child's timeline. SSY is also available only for a girl child meeting the scheme's age and eligibility conditions, so it cannot be the universal solution for every education goal. Where mutual funds fit Diversified equity-oriented funds can provide long-horizon growth potential but fluctuate materially, including near the date the money is needed. Debt-oriented or other lower-volatility funds may be used differently depending on horizon, tax treatment and risk. The key advantage is flexibility: parents can create a goal-specific portfolio and gradually reduce risk as college approaches. The trade-off is that there is no guaranteed return or government-set maturity value. A blended approach Instead of asking SSY or mutual funds, some families may use SSY as a stable long-term layer and market-linked investments for the portion requiring higher growth or greater flexibility. The combined target should still be calculated from the future education cost. Do not fund SSY to the maximum automatically if doing so leaves retirement, emergency reserves or insurance underfunded. De-risk as admission approaches An education corpus is different from retirement because the payment date is relatively fixed. A market fall one year before admission cannot simply be solved by postponing college for five years. As the goal moves closer, progressively shift the amount needed for near-term fees from volatile assets into appropriate lower-risk and liquid instruments. Frequently Asked Questions Is SSY guaranteed? It is a government small-savings scheme; interest rates are notified periodically and scheme rules apply. Can SSY alone fund an expensive overseas degree? It depends on contributions, time and future cost. Calculate the target rather than assuming one product is sufficient. Are mutual funds too risky for education? Risk depends on the fund and time horizon. Equity can be unsuitable for money needed very soon but useful for sufficiently long horizons. Should I choose the product with the highest recent return? No. Match the investment to the goal date, required return, liquidity and risk capacity. Related Reading Child Education Planning in India (/insights/child-education-planning-guide-india) Children's Funds (/insights/childrens-funds) SIP Planning Guide (/insights/sip-planning-guide-india) Disclaimer: This article is for general educational purposes only and is not personalised investment, tax, legal or regulatory advice. Rules, rates and product terms change. Readers should verify current provisions and obtain professional advice appropriate to their circumstances before acting.