Annuity Plans vs NPS Annuity: Rates, Options and Tax in 2026
Last updated: 13 October 2026
Quick answer: An insurer annuity plan and an NPS annuity are the same kind of contract: you hand a lump sum to a life insurer for a guaranteed pension. The difference is the money. An NPS annuity must use at least 20% of a non-government corpus above ₹12 lakh (40% for government staff) and comes from an empanelled insurer. Either way, the pension is taxed at your slab rate.
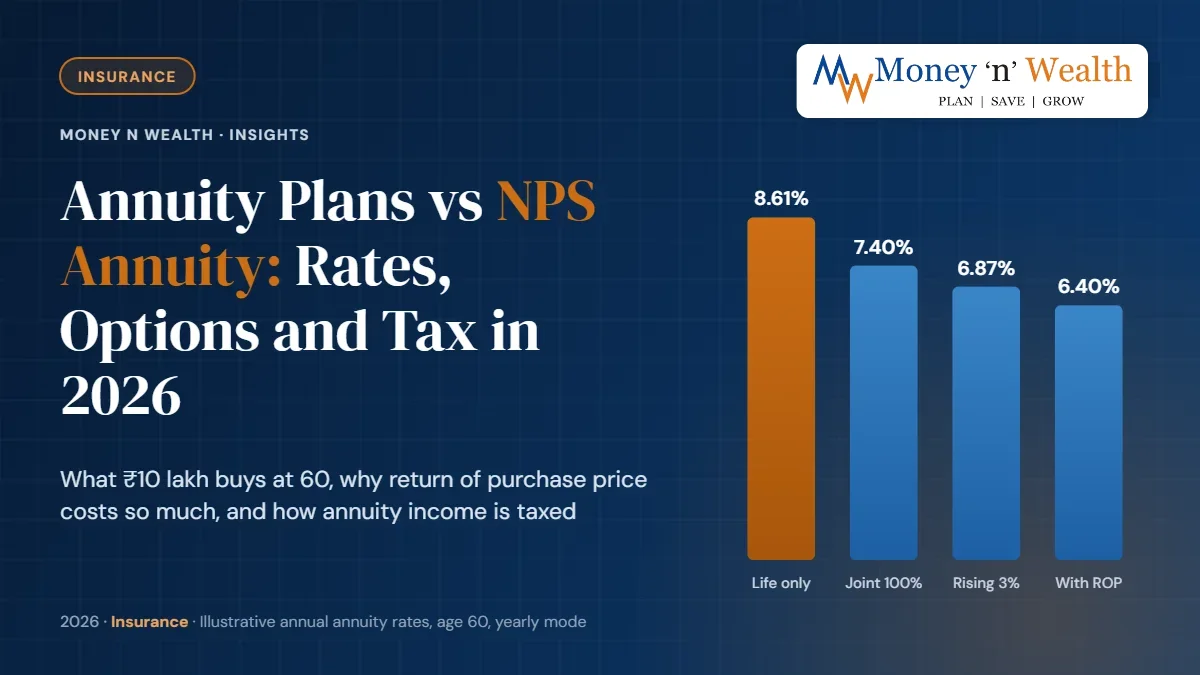
Last updated: 13 October 2026 Quick answer: An insurer annuity plan and an NPS annuity are the same kind of contract: you hand a lump sum to a life insurer for a guaranteed pension. The difference is the money. An NPS annuity must use at least 20% of a non-government corpus above ₹12 lakh (40% for government staff) and comes from an empanelled insurer. Either way, the pension is taxed at your slab rate. Key takeaways Rates at 60: about 8.6% a year for a plain life annuity, 6.4% with return of purchase price (illustrative, yearly mode). Return of price is costly: it pays more to the family only if the annuitant dies before about 82. Fully taxable: annuity income is taxed at slab under "other sources", with no standard deduction and no split for return of capital. NPS rule from Dec 2025: non-government subscribers can take 80% as a lump sum, but only 60% is clearly tax-free. No GST: individual annuity plans have been GST-free since 22 September 2025. A 60-year-old retiring from a Pune IT firm has ₹1 crore in NPS and ₹50 lakh in savings. Her NPS exit form asks how much to use for an annuity. Her bank's relationship manager is pitching a "guaranteed pension plan" for the savings. Both are annuities, both are irreversible, and both are taxed in ways most brochures skip. This guide compares insurer annuity plans with the NPS annuity as of October 2026: immediate and deferred annuities, the main payout options, what return of purchase price really costs, how annuity income is taxed, and what the 2025-26 PFRDA changes mean for the choice. What is an annuity, and how does it work? An annuity is a contract in which you pay a life insurer a lump sum, called the purchase price, and it pays you a fixed income for life or for a set period. The insurer takes on the risk that you live longer than expected. The rate is fixed on the day you buy and does not change with future interest rates. In India, annuities are sold by life insurers under IRDAI rules. You can buy one with your own money, or with the mandatory portion of your NPS corpus, in which case it must come from an Annuity Service Provider (ASP) empanelled by PFRDA. Immediate vs deferred annuity An immediate annuity starts paying from the next month, quarter or year after purchase. It suits people who are already retired and need income now. An NPS annuity at exit is usually immediate. A deferred annuity is bought now (with a single premium or a series of payments) and starts paying after a chosen deferment period, say from 55 to 60. The insurer holds the money longer, so the eventual pension per rupee is higher. The trade-off is that your money is locked in, often with limited exit options, long before you need the income. Which annuity option gives the highest pension? The more the insurer promises to pay after you die, the less it pays while you live. The table below uses illustrative quotes for LIC's Jeevan Akshay VII at age 60, yearly mode, as reported in August–October 2026, scaled to a ₹50 lakh purchase. Quotes from other insurers and for monthly payouts will differ, so treat these as a guide to the trade-offs, not a price list. Annuity option (age 60) Rate a year Pension on ₹50 lakh What happens at death Life annuity 8.61% ₹4,30,500 Payments stop; nothing returned Life, 10 years guaranteed 8.40% ₹4,20,000 Paid to nominee for the rest of 10 years Joint life, 50% to spouse 7.96% ₹3,98,000 Spouse gets half for life Joint life, 100% to spouse 7.40% ₹3,70,000 Spouse gets full pension for life Life, rising 3% a year (simple) 6.87% ₹3,43,500 in year 1 Payments stop Life with return of purchase price 6.40% ₹3,20,000 ₹50 lakh to nominee Joint life with return of purchase price 6.33% ₹3,16,500 Spouse continues; ₹50 lakh after both Illustrative rates for ₹10 lakh at age 60 (spouse 55), yearly mode, as reported by Ditto Insurance; Money n Wealth scaling to ₹50 lakh. Get a current quote before deciding. Horizontal bar chart comparing annuity plan pensions from ₹50 lakh at age 60 across life, joint life and return of purchase price options What return of purchase price really costs Return of purchase price (ROP) sounds like the safe choice: you get a pension and your children get the money back. But on ₹50 lakh, it costs ₹1,10,500 a year in pension compared with a plain life annuity. That is the price of the legacy. We worked out the return to the family under each option, by the age at which the annuitant dies. ROP always yields its 6.40% because the capital comes back. The plain life annuity yields less if death comes early, but overtakes ROP at about age 82. By 90, it delivers 7.67%. Line chart of internal rate of return of a life annuity versus return of purchase price annuity by age at death Two further points. The ₹50 lakh returned after 25 years will buy far less than ₹50 lakh does today. And a family that wants a legacy can often get one more cheaply with a term policy or by keeping some savings invested, while using a higher-paying life annuity for income. Our guide on working out the real IRR of guaranteed plans (/insights/guaranteed-return-endowment-plan-real-irr) uses the same method. Inflation is the annuity's blind spot Most annuities pay a fixed rupee amount. At 5% inflation, a ₹4.31 lakh pension buys only ₹2.64 lakh of today's goods after 10 years and ₹1.62 lakh after 20. The 3% rising option helps: it overtakes the level annuity in year 10 and catches up in total payouts by year 18. That suits someone in good health with a long family history of longevity. Bar chart showing how inflation erodes a fixed annuity pension over 30 years How is annuity income taxed in India? Annuity income is fully taxable in the year you receive it, at your slab rate. For an annuity you buy yourself, or one bought from your individual NPS account, it is taxed under "income from other sources". The ₹75,000 standard deduction for pensioners under the new regime does not apply, because that is available only on pension taxed as salary, such as EPS pension or an annuity bought by an employer. The annuity is also not interest. So the old-regime deduction of up to ₹50,000 on senior citizens' interest income does not cover it. And unlike some countries, India does not exempt the part of each payment that is really your own capital coming back. In the United States, for instance, the IRS treats the portion of each annuity payment that reflects your after-tax cost as tax-free. Annuity option Pre-tax yield After tax at 20.8% After tax at 31.2% Life annuity 8.61% 6.82% 5.92% Joint life, 100% to spouse 7.40% 5.86% 5.09% Life with return of purchase price 6.40% 5.07% 4.40% Joint life with return of purchase price 6.33% 5.01% 4.36% Rates include 4% cess on 20% and 30% slabs. Many retirees pay much less. Under the new regime for FY 2026-27, income up to ₹12 lakh effectively attracts no tax because of the rebate, so a retiree whose total income is an annuity of ₹4–5 lakh may pay nothing. Our senior citizen tax planning guide (/insights/senior-citizen-tax-planning-interest-pension-rent) shows how pension, interest and rent combine. On GST, individual life and annuity plans have been exempt since 22 September 2025, so a single-premium annuity no longer carries GST on the purchase price. How does the NPS annuity differ from an insurer annuity plan? The contract is the same type; the source of money and the rules differ. Comparison of insurer annuity plans and NPS annuity on eligibility, choice and tax How much of your NPS corpus must buy an annuity in 2026? PFRDA's amended exit regulations, notified in December 2025, changed the split for normal exit at 60 or later: Corpus at normal exit Non-government subscriber Government sector subscriber Up to ₹8 lakh 100% can be withdrawn 100% can be withdrawn ₹8 lakh to ₹12 lakh Up to ₹6 lakh lump sum; rest by annuity or systematic unit redemption over at least 6 years Similar small-corpus route Above ₹12 lakh At least 20% annuity; up to 80% lump sum At least 40% annuity; up to 60% lump sum You may defer both the lump sum and the annuity purchase up to age 85. A 20% minimum is a floor, not a target: you can use more of the corpus for an annuity if you want more guaranteed income. Our guides to the five NPS annuity options (/insights/nps-annuity-options-five-payout-choices) and NPS changes in 2026 (/insights/nps-changes-2026-investor-guide) cover the detail, and NPS payout choices (/insights/nps-payout-ris-annuity-systematic-withdrawal) explains the new Retirement Income Schemes, which pay out the lump-sum portion but do not replace the mandatory annuity. The tax quirk that favours annuitising inside NPS Only 60% of the NPS corpus is clearly tax-free at exit. Budget 2026 did not extend that exemption to the new 80% limit, so the extra 20% may be taxable at your slab. The amount used to buy the annuity, however, is not taxed at exit. Take a ₹1 crore corpus. Withdraw 80%, and up to ₹20 lakh could be taxable: at 31.2%, about ₹6.24 lakh. If you then buy an annuity outside NPS with what is left of that ₹20 lakh, you have only ₹13.76 lakh to invest, which buys about ₹1.18 lakh a year. Leave the same ₹20 lakh inside NPS for a 40% annuity, and it buys about ₹1.72 lakh a year, with no tax on the purchase. Stacked bar comparing an 80:20 and 60:40 NPS exit split with the NPS annuity and possible tax So if you were going to buy an annuity anyway, buying it with NPS money is usually more tax-efficient than withdrawing first. If you want flexibility rather than guaranteed income, the extra 20% may still be worth taking, but plan for the tax. See NPS after 60: withdraw, defer or continue (/insights/nps-after-60-withdraw-defer-or-continue) for the timing choices. When does an insurer annuity plan make sense? An annuity is the only product that guarantees income for as long as you live, however long that is. It makes sense for a part of retirement money when: Your guaranteed income (pension, rent, EPS) does not cover essential expenses. You worry about outliving your savings, or about managing investments in your late 70s and 80s. A spouse with little income of their own needs protection; a joint-life option handles that. You want predictability more than growth for one bucket of money. It is a poor fit for money you may need in an emergency, for people with serious health conditions (who are unlikely to live long enough to benefit, unless an insurer offers enhanced rates), and for all of a retiree's savings, because the rupee amount does not grow. Annuity vs SCSS, FDs and SWP Option Income on ₹30 lakh How long Capital Tax Life annuity (illustrative 8.61%) ₹2,58,300 a year For life Not returned Slab rate SCSS (8.2%, Oct–Dec 2026) ₹2,46,000 a year 5 years, extendable Returned Slab rate Bank FD Depends on rate Fixed term Returned Slab rate Mutual fund SWP You choose Until corpus runs out Market-linked Capital gains on units sold SCSS pays almost as much and returns your capital, but only for five-year terms, within a ₹30 lakh limit, and at whatever rate applies when you renew. An SWP from mutual funds (/insights/swp-systematic-withdrawal-plan-guide) can grow with markets and is taxed more lightly, but carries market and longevity risk. Many retirees use a layered approach, as our retirement income strategy guide (/insights/retirement-income-strategy-india) describes: annuity and SCSS for the floor, a bucket of debt funds for the next few years, and equity for later decades. Does the October 2026 rate hike change the timing? Annuity rates broadly follow long-term government bond yields. After the RBI raised the repo rate to 5.50% on 7 October 2026, the 10-year G-sec yield was around 7.25%. Higher yields tend to support annuity quotes, but there is no way to know where they go next. If you are buying a large annuity, consider buying in two or three tranches over a few years instead of all at once. See our note on the October 2026 rate hike (/insights/rbi-repo-rate-hike-october-2026-emi-fd-debt-funds) . How to choose an annuity: a five-step checklist Size the gap. List essential monthly expenses and subtract guaranteed income. Annuitise to cover part or all of that gap, not more. Decide who needs protecting. If a spouse depends on your income, choose a joint-life option, usually with 100% continuation if the spouse has no pension. Decide on legacy separately. Compare the pension you give up for return of purchase price with the cost of a term policy or simply leaving other assets. Compare quotes on the same basis. Same age, amount, option and payout mode, across at least three insurers or empanelled ASPs. Check the insurer and the fine print. Look at surrender conditions, death-benefit definitions and the insurer's service record. Our guide to mis-selling red flags (/insights/mis-selling-red-flags-insurance-investments) lists the warning signs. Related reading NPS annuity options: five payout choices (/insights/nps-annuity-options-five-payout-choices) NPS after 60: withdraw, defer or continue (/insights/nps-after-60-withdraw-defer-or-continue) Retirement income for 25 years: pension, rent or SWP? (/insights/retirement-income-pension-rent-or-swp-25-years) Senior Citizens' Savings Scheme guide (/insights/senior-citizens-savings-scheme-scss-guide) Retirement planning for couples (/insights/retirement-planning-for-couples-india) NPS through Money n Wealth (/products/nps) Frequently Asked Questions What is the difference between an NPS annuity and an annuity plan from an insurer? Both are annuity contracts issued by life insurers. An NPS annuity is bought with the mandatory portion of your NPS corpus at exit (at least 20% for non-government and 40% for government subscribers with more than ₹12 lakh) from a PFRDA-empanelled insurer. An insurer annuity plan is bought with any money you choose. The pension from both is taxed at your slab rate. Is annuity income taxable in India? Yes. Annuity income is fully taxable at your slab rate in the year you receive it. An annuity bought by you or from your individual NPS account is taxed as income from other sources, without the standard deduction. Only an annuity bought by your employer is treated as salary. There is no exemption for the part of each payment that returns your capital. Which annuity option gives the highest pension? A single-life annuity with no return of purchase price pays the most, about 8.6% a year at age 60 in recent illustrative quotes. Each extra feature, such as a guaranteed period, spouse continuation, annual increases or return of purchase price, lowers the starting pension. Return of purchase price options paid around 6.3–6.4% in the same quotes. Is return of purchase price worth it? Only if leaving the original amount to heirs is a priority. In our calculation at age 60, a plain life annuity gives the family a better return than the return-of-price option if the annuitant lives beyond about 82. The returned capital also loses value to inflation. A term policy or other assets may provide a legacy more cheaply. How much of my NPS must I use to buy an annuity in 2026? Under PFRDA's December 2025 amendment, non-government subscribers with more than ₹12 lakh at normal exit must use at least 20% for an annuity and may withdraw up to 80%. Government-sector subscribers must use at least 40%. A corpus of ₹8 lakh or less can be fully withdrawn, and you can defer the annuity purchase up to age 85. Can I surrender an annuity plan? Generally, an immediate annuity cannot be surrendered once payments start. Some return-of-purchase-price plans allow a surrender or loan in specified situations, such as diagnosis of a listed critical illness, often with deductions. Read the policy's surrender conditions before buying, and keep money you may need for emergencies outside the annuity. Is GST charged on annuity plans? Not on individual plans. From 22 September 2025, GST on individual life insurance premiums was cut to zero, and insurers apply this to individual pension and annuity plans. Group and employer-funded pension products still attract GST. Sources: Ditto Insurance on LIC Jeevan Akshay VII rates (https://joinditto.in/articles/life-insurance/lic-jeevan-akshay-vii/) ; Protean CRA on December 2025 NPS exit changes (https://proteantech.in/articles/nps-withdrawal-rules-2025-changes-december/) ; Upstox on standard deduction and annuity tax (https://upstox.com/news/personal-finance/tax/can-i-claim-rs-75000-standard-deduction-on-lic-annuity-eps-and-nps-in-itr-for-ay-2026-27/article-196516/) ; Outlook Business on annuity vs interest income (https://www.outlookbusiness.com/amp/story/personal-finance/tax/annuity-is-not-taxed-as-interest-income-cannot-be-claimed-as-deduction-under-section-80ttb) ; Department of Financial Services on GST exemption (https://financialservices.gov.in/node/3332) ; Axis Max Life on GST on pension plans (https://www.axismaxlife.com/blog/retirement-planning/gst-on-pension) ; IRS Topic 411 on annuity taxation (US) (https://www.irs.gov/taxtopics/tc411) . Worked examples are Money n Wealth calculations. Deciding how much of your retirement money to annuitise? The right mix of annuity, NPS withdrawal, SCSS and investments depends on your expenses, health and family. Talk to Money n Wealth (/contact) for a free retirement income review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it. Insurance is the subject matter of solicitation.
Frequently Asked Questions
What is the difference between an NPS annuity and an annuity plan from an insurer?
Both are annuity contracts issued by life insurers. An NPS annuity is bought with the mandatory portion of your NPS corpus at exit (at least 20% for non-government and 40% for government subscribers with more than ₹12 lakh) from a PFRDA-empanelled insurer. An insurer annuity plan is bought with any money you choose. The pension from both is taxed at your slab rate.
Is annuity income taxable in India?
Yes. Annuity income is fully taxable at your slab rate in the year you receive it. An annuity bought by you or from your individual NPS account is taxed as income from other sources, without the standard deduction. Only an annuity bought by your employer is treated as salary. There is no exemption for the part of each payment that returns your capital.
Which annuity option gives the highest pension?
A single-life annuity with no return of purchase price pays the most, about 8.6% a year at age 60 in recent illustrative quotes. Each extra feature, such as a guaranteed period, spouse continuation, annual increases or return of purchase price, lowers the starting pension. Return of purchase price options paid around 6.3–6.4% in the same quotes.
Is return of purchase price worth it?
Only if leaving the original amount to heirs is a priority. In our calculation at age 60, a plain life annuity gives the family a better return than the return-of-price option if the annuitant lives beyond about 82. The returned capital also loses value to inflation. A term policy or other assets may provide a legacy more cheaply.
How much of my NPS must I use to buy an annuity in 2026?
Under PFRDA's December 2025 amendment, non-government subscribers with more than ₹12 lakh at normal exit must use at least 20% for an annuity and may withdraw up to 80%. Government-sector subscribers must use at least 40%. A corpus of ₹8 lakh or less can be fully withdrawn, and you can defer the annuity purchase up to age 85.
Can I surrender an annuity plan?
Generally, an immediate annuity cannot be surrendered once payments start. Some return-of-purchase-price plans allow a surrender or loan in specified situations, such as diagnosis of a listed critical illness, often with deductions. Read the policy's surrender conditions before buying, and keep money you may need for emergencies outside the annuity.
Is GST charged on annuity plans?
Not on individual plans. From 22 September 2025, GST on individual life insurance premiums was cut to zero, and insurers apply this to individual pension and annuity plans. Group and employer-funded pension products still attract GST.
Deciding how much of your retirement money to annuitise?
The right mix of annuity, NPS withdrawal, SCSS and investments depends on your expenses, health and family. Talk to Money n Wealth for a free retirement income review.