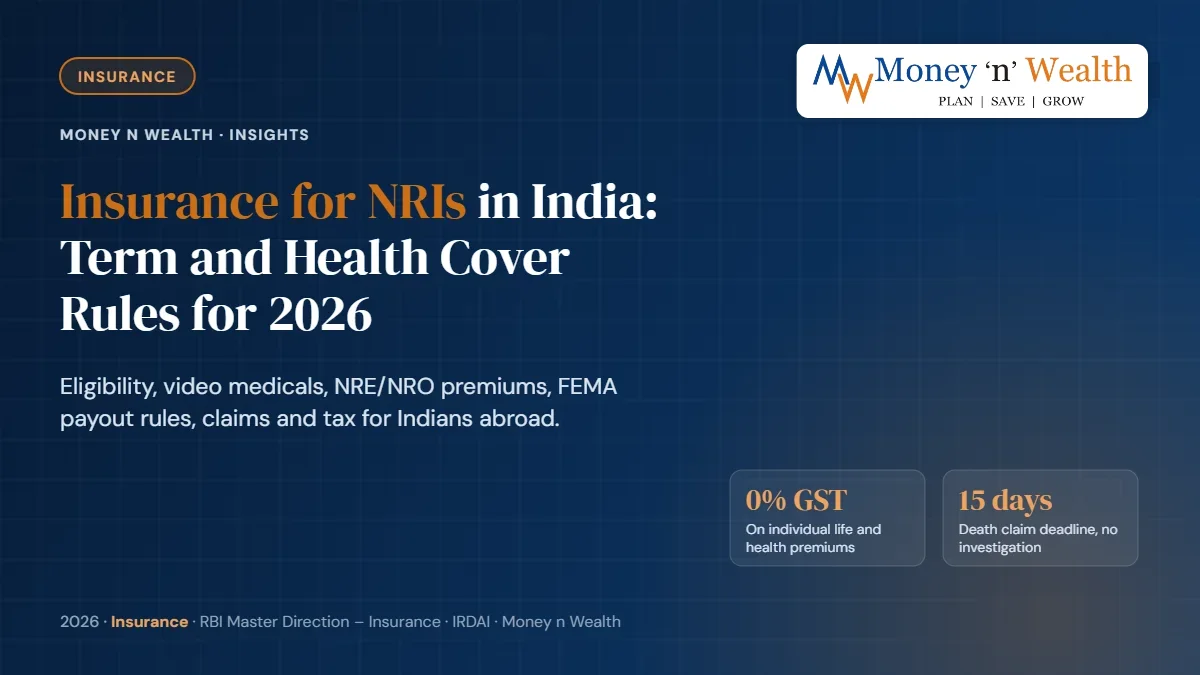
Insurance for NRIs in India: Term and Health Cover Rules for 2026
Last updated: 13 October 2026
Quick answer: Yes, NRIs can buy life and health insurance from Indian insurers. Term cover can usually be bought online from abroad, with video or tele-medicals, and pays out wherever death occurs. Premiums can come from NRE, FCNR, NRO or remittances; RBI rules let proceeds be repatriated in proportion to premiums paid in foreign exchange. Indian health policies generally cover treatment only in India.
Last updated: 13 October 2026 Quick answer: Yes, NRIs can buy life and health insurance from Indian insurers. Term cover can usually be bought online from abroad, with video or tele-medicals, and pays out wherever death occurs. Premiums can come from NRE, FCNR, NRO or remittances; RBI rules let proceeds be repatriated in proportion to premiums paid in foreign exchange. Indian health policies generally cover treatment only in India. Key takeaways Eligibility: NRIs, OCIs and PIOs can apply; acceptance and limits depend on residence country. Premium source matters: NRE/FCNR or remittance keeps claims repatriable; NRO-paid policies pay out in rupees. Health cover: Indian plans pay for treatment in India; useful for parents and returning NRIs, not as primary overseas cover. Claims: 15 days for death claims without investigation, 45 days with, under IRDAI's 2024 master circular. Tax: death benefit is tax-free in India; GST on individual premiums is nil since 22 September 2025. An engineer in Dallas with two children in school pays several times more for a US term policy than his cousin in Pune pays for similar cover in India. Not surprisingly, many NRIs ask whether they can simply buy an Indian policy instead. The answer is usually yes, but the details decide whether the policy actually works when it is needed. This guide covers who can buy insurance for NRIs from Indian insurers, how medicals happen from abroad, how premiums must be paid under FEMA, how claims are paid to nominees overseas, and the tax position in India, all as of October 2026. Can NRIs buy term insurance in India? Yes. Indian life insurers issue policies to non-resident Indians, Overseas Citizens of India and persons of Indian origin. A term plan is a pure life cover: if the insured dies during the term, the nominee receives the sum assured. It pays regardless of the country where death occurs, subject to the policy terms. What changes for an NRI is underwriting. Insurers group residence countries into bands based on mortality, health-care standards and geopolitical risk. Commonly accepted countries such as the US, UK, Canada, Singapore, Australia and the Gulf states usually get standard terms. Other countries may face lower maximum covers or extra premium loading. Some countries , typically those under sanctions or in conflict, are not accepted at all. Lists differ by insurer and change periodically. Check your country and the maximum sum assured before you start, not after the medicals. Documents usually required Passport with valid visa, residence permit or OCI card. Overseas address proof and Indian address, if any. Income proof, typically recent salary slips, employment letter or overseas tax returns. FATCA/CRS self-declaration of tax residency. Do NRIs need to come to India for medical tests? Often not. Most large insurers now allow the proposal, KYC and payment to be completed online. Medical underwriting happens in one of three ways: Route How it works Typical fit Tele-medical or video medical A doctor interviews you by phone or video; reports you already have may be requested Younger, healthy applicants with moderate cover Tests abroad Tests at a lab or empanelled centre in your country of residence, where the insurer allows it Larger covers in accepted countries Tests during an India visit Full medicals at a diagnostic centre in India High covers, older applicants or health history Video medicals are generally limited to lower sums assured. If you want a large cover, plan the application around your next India trip. Whatever the route, the risk starts only when the insurer issues the policy, not when you pay. Disclosure matters even more for NRIs. Declare existing overseas policies, health history and habits. Non-disclosure remains the leading cause of rejected death claims, as our guide to claim settlement ratios (/insights/claim-settlement-ratio-explained) explains. How can NRIs pay insurance premiums under FEMA? The rules sit in RBI's Master Direction – Insurance (FED Master Direction No. 9/2015-16, issued under FEMA, 1999). Indian insurers may issue rupee policies to NRIs and accept premiums from several sources: Inward remittance from abroad through banking channels. The policyholder's NRE or FCNR account. The policyholder's NRO account (rupee funds). In some cases, accounts of close resident relatives, though this restricts how the claim can later be paid abroad. Auto-debit (e-NACH) from an NRE or NRO account is the practical choice. Card payments are accepted by many insurers but check whether the insurer records them as foreign-exchange receipts. How the premium payment source for insurance for NRIs decides repatriation of claim proceeds Why the payment source matters at claim time RBI permits claim and maturity payments in foreign currency only in the proportion in which premiums were paid in foreign exchange. Non-resident beneficiaries may have proceeds credited to their NRE or FCNR account. Where premiums came from non-repatriable rupees, payment is made in rupees to the beneficiary's NRO account. So if your spouse and children live abroad, pay from NRE or by remittance from day one, and keep premium receipts. Moving money out of NRO later is possible within limits, but it adds paperwork, certificates and delays when your family can least afford them. How much term cover should an NRI buy, and in which currency? Size the cover on what your family would spend, in the country where they would live. An Indian policy pays in rupees, so a family that would stay in the US or UK is exposed to rupee depreciation over a 25 to 30-year term. A practical approach many NRIs use: Work out the family's need in local currency: living costs until children are independent, loans and education. Convert to rupees at today's rate and add a margin of 20% to 30% for currency movement. Check whether one Indian policy at that size is allowed for your country. If not, combine an Indian and a local policy. If the family would return to India after a death, size the cover in rupee terms instead. Our guide on how much term cover you need (/insights/term-insurance-advisor-pune) walks through the maths. Employer life cover abroad usually ends when the job ends. Treat it as a bonus, not the base. Comparison of term life insurance vs health insurance from Indian insurers for NRIs Can NRIs buy health insurance in India? Yes, but understand its limits. Indian individual health policies generally pay only for treatment taken in India. They do not replace health cover in your country of residence. Insurer practice also varies. Some issue health policies to NRIs freely; others require Indian residence or a minimum stay in India during the year. Read the proposal form and declare your residence honestly; a mismatch can be used to deny a claim. When an Indian health policy makes sense for an NRI You plan to return within a few years. Waiting periods start running now. Under IRDAI's 2024 health master circular, the pre-existing disease waiting period is capped at three years, and policies cannot be contested on non-disclosure after five continuous years (the moratorium). You want cover for parents in India. You can buy and pay for a policy covering them. See our guide to health insurance for parents and senior citizens (/insights/health-insurance-for-parents-senior-citizens) . You come to India for planned treatment. Many overseas policies cover only emergencies abroad and exclude elective surgery in India, so check before you fly. Combine a modest base policy with a super top-up (/insights/super-top-up-health-insurance) for cost efficiency, and keep it continuous. If you later switch insurers, portability rules (/insights/health-insurance-portability-rules) carry the waiting-period credit. How do NRI nominees make a claim? Death claims follow the same IRDAI timelines for everyone. Under the Master Circular on Protection of Policyholders' Interests (5 September 2024), a claim needing no investigation must be settled within 15 days of intimation, and one needing investigation within 45 days. Delays attract interest at bank rate plus 2%. The practical difference is documentation when death occurs abroad: Intimate the claim online or by email with the policy number. Most insurers accept claims from overseas. Death certificate issued by the foreign authority, usually attested by the Indian embassy or consulate or apostilled, with an English translation if needed. Medical records or police report for illness or accidental death, as applicable. Nominee KYC : passport, overseas address proof and bank details (NRE/FCNR or NRO, matching the payment rules). Policy document and claim form , plus any additional papers the insurer asks for. Store scanned copies and a one-page instruction note where your nominee can find them. Our estate planning guide (/insights/estate-planning-guide-india) explains why nominees and wills should line up. Six steps to buy term insurance for NRI from an Indian insurer while living abroad How are NRI insurance premiums and payouts taxed? In India Item Tax treatment (as of October 2026) Life premium deduction Up to ₹1.5 lakh under section 123 of the Income-tax Act, 2025 (old 80C), old regime only and only if you have taxable Indian income Health premium deduction Available under the old regime (old section 80D, renumbered in the 2025 Act), for self, family and parents Death benefit to nominee Exempt Maturity or surrender of savings plans Exempt only if premium-to-sum-assured and aggregate premium conditions are met; otherwise taxable, with TDS under non-resident rates GST on premium Nil for individual life and health policies since 22 September 2025 Term plans with no maturity benefit avoid the maturity-tax questions altogether. Our NRI taxation guide (/insights/nri-taxation-india-guide) covers residency tests, TDS and DTAA relief in detail. Key numbers on claims, waiting periods and tax for insurance for NRIs in India In your country of residence Pure term cover rarely creates reporting problems abroad. Cash-value policies such as endowment, money-back and ULIPs can. In the US, for example, they may need to be reported as foreign financial assets and can face complex tax treatment. Before buying anything other than a pure term plan, check with a tax adviser in your country. Our article on hidden tax and reporting risks across borders (/insights/foreign-investing-tax-estate-risk-india) explains the US angle. What happens to the policy if you return to India or move abroad? An Indian life policy does not lapse because your residence changes. You must inform the insurer, update KYC and FATCA/CRS status, and switch the premium mandate to the right account type. On becoming non-resident, resident savings accounts must be redesignated, so set up the NRO or NRE mandate in time to avoid a lapse. Health policies are different. If the insurer's terms required Indian residence, moving abroad may affect renewals. Ask in writing before you relocate. Returning NRIs should buy health cover a year or two before moving back, so waiting periods are largely done on arrival. A checklist before you buy Is my residence country accepted, and what is the maximum cover? Which medical route applies to my age and cover? Will I pay from NRE/FCNR so the claim stays repatriable? Have I sized cover for my family's currency and location? Have I disclosed overseas policies and health history fully? Does my nominee know where the documents are? Money n Wealth distributes Tata AIA and Tata AIG insurance and works with NRIs from Pune. We do not rank insurers; the checklist above applies to any insurer. See our page on NRI investing from Pune (/insights/nri-investment-advisor-in-pune) and our insurance services (/products/insurance) . Related reading NRI taxation in India: residency, TDS, DTAA (/insights/nri-taxation-india-guide) Claim settlement ratio: how to read it properly (/insights/claim-settlement-ratio-explained) Health insurance for parents and senior citizens (/insights/health-insurance-for-parents-senior-citizens) Term insurance for homemakers and women (/insights/term-insurance-for-homemakers-women) Insurance planning in India: term, health, life (/insights/insurance-planning-guide-india) Frequently Asked Questions Can an NRI buy term insurance in India while living abroad? Yes. Most Indian life insurers let NRIs apply online with passport, visa and overseas address proof. Medicals can often be done by video or tele-call for moderate covers, or at a lab abroad or during an India visit for larger covers. Acceptance and maximum cover depend on your country of residence, so check that first. Can NRIs pay insurance premiums from an NRE account? Yes. Under RBI's Master Direction on insurance, premiums can be paid from NRE, FCNR or NRO accounts or by remittance from abroad. Paying from NRE, FCNR or remittance lets the claim be repatriated in foreign currency in proportion to those premiums. NRO-funded policies are paid in rupees to an NRO account. Will an Indian term policy pay if the NRI dies abroad? Yes. A term plan pays on death during the term regardless of where it occurs, subject to policy exclusions and correct disclosure. Nominees need the foreign death certificate, usually attested by the Indian embassy or apostilled, plus KYC and bank details. IRDAI timelines of 15 or 45 days apply once documents are complete. Is Indian health insurance valid abroad for NRIs? Generally no. Standard Indian individual health policies pay only for treatment in Indian hospitals. They suit NRIs who visit often, plan to return, or want cover for parents in India. For treatment in your country of residence, you need a local or international health policy. Is the life insurance death benefit taxable for NRI nominees? No, the death benefit from a life policy is exempt from income tax in India. Nominees resident abroad should check their own country's rules, though pure term payouts are usually not taxed as income in most countries. Maturity proceeds from savings plans are a different matter and may be taxable in India and abroad. Can NRIs claim tax deductions on insurance premiums? Only if they have taxable income in India and choose the old tax regime. Life premiums then qualify for up to ₹1.5 lakh under section 123 of the Income-tax Act, 2025, and health premiums qualify under the renumbered old section 80D. Under the default new regime, there is no deduction. What happens to my policy if I return to India? Your life policy continues. Inform the insurer, update KYC and tax residency, and switch premium payments to a resident account. Health policies continue too, and any waiting periods already served count. Returning NRIs should ideally buy health cover a year or two before moving back. Sources: RBI Master Direction – Insurance (https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=10194) ; LIC conditions for NRI proposals (https://licindia.in/documents/d/guest/annexure-iii-) ; Mondaq on IRDAI 2024 policyholder master circular (https://www.mondaq.com/india/insurance-laws-and-products/1536672/irdai39s-update-on-turnaround-times-for-insurance-companies) ; NRI Information, life insurance rules (https://nriinformation.com/nri-info/life-insurance-rules) ; Ditto, health insurance for NRIs (https://joinditto.in/articles/health-insurance/ditto-health-insurance-guide-for-nri/) ; Outlook Money on NRIs and overseas health cover (https://www.outlookmoney.com/personal-finance/nris-coming-home-for-surgery-are-hitting-an-unexpected-roadblock-their-global-insurance-doesnt-always-pay) ; Business Today on GST exemption (https://www.businesstoday.in/india/story/big-relief-health-and-life-insurance-exempted-from-gst-as-council-scraps-12-and-28-slabs-492405-2025-09-03) . Living abroad and unsure how to protect your family back home? Country rules, payment sources and nominee paperwork are easy to get wrong from a distance. Talk to Money n Wealth (/contact) for an insurance review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it. Insurance is the subject matter of solicitation.
Frequently Asked Questions
Can an NRI buy term insurance in India while living abroad?
Yes. Most Indian life insurers let NRIs apply online with passport, visa and overseas address proof. Medicals can often be done by video or tele-call for moderate covers, or at a lab abroad or during an India visit for larger covers. Acceptance and maximum cover depend on your country of residence, so check that first.
Can NRIs pay insurance premiums from an NRE account?
Yes. Under RBI's Master Direction on insurance, premiums can be paid from NRE, FCNR or NRO accounts or by remittance from abroad. Paying from NRE, FCNR or remittance lets the claim be repatriated in foreign currency in proportion to those premiums. NRO-funded policies are paid in rupees to an NRO account.
Will an Indian term policy pay if the NRI dies abroad?
Yes. A term plan pays on death during the term regardless of where it occurs, subject to policy exclusions and correct disclosure. Nominees need the foreign death certificate, usually attested by the Indian embassy or apostilled, plus KYC and bank details. IRDAI timelines of 15 or 45 days apply once documents are complete.
Is Indian health insurance valid abroad for NRIs?
Generally no. Standard Indian individual health policies pay only for treatment in Indian hospitals. They suit NRIs who visit often, plan to return, or want cover for parents in India. For treatment in your country of residence, you need a local or international health policy.
Is the life insurance death benefit taxable for NRI nominees?
No, the death benefit from a life policy is exempt from income tax in India. Nominees resident abroad should check their own country's rules, though pure term payouts are usually not taxed as income in most countries. Maturity proceeds from savings plans are a different matter and may be taxable in India and abroad.
Can NRIs claim tax deductions on insurance premiums?
Only if they have taxable income in India and choose the old tax regime. Life premiums then qualify for up to ₹1.5 lakh under section 123 of the Income-tax Act, 2025, and health premiums qualify under the renumbered old section 80D. Under the default new regime, there is no deduction.
What happens to my policy if I return to India?
Your life policy continues. Inform the insurer, update KYC and tax residency, and switch premium payments to a resident account. Health policies continue too, and any waiting periods already served count. Returning NRIs should ideally buy health cover a year or two before moving back.
Living abroad and unsure how to protect your family back home?
Country rules, payment sources and nominee paperwork are easy to get wrong from a distance. Talk to Money n Wealth for an insurance review.