Insurance Advisor in Pune: A Complete Guide to Life, Health and General Insurance Planning
Ask most people to describe their financial plan and they'll talk about SIPs, stocks, or a PPF account. Ask about their insurance and the answer is vaguer — "I have some cover through work" or "not sure how much." As an insurance advisor working across Pune, our starting point is always the same: insurance isn't bought once and forgotten — it's the foundation that protects investments, savings and goals from being derailed by a single bad event.
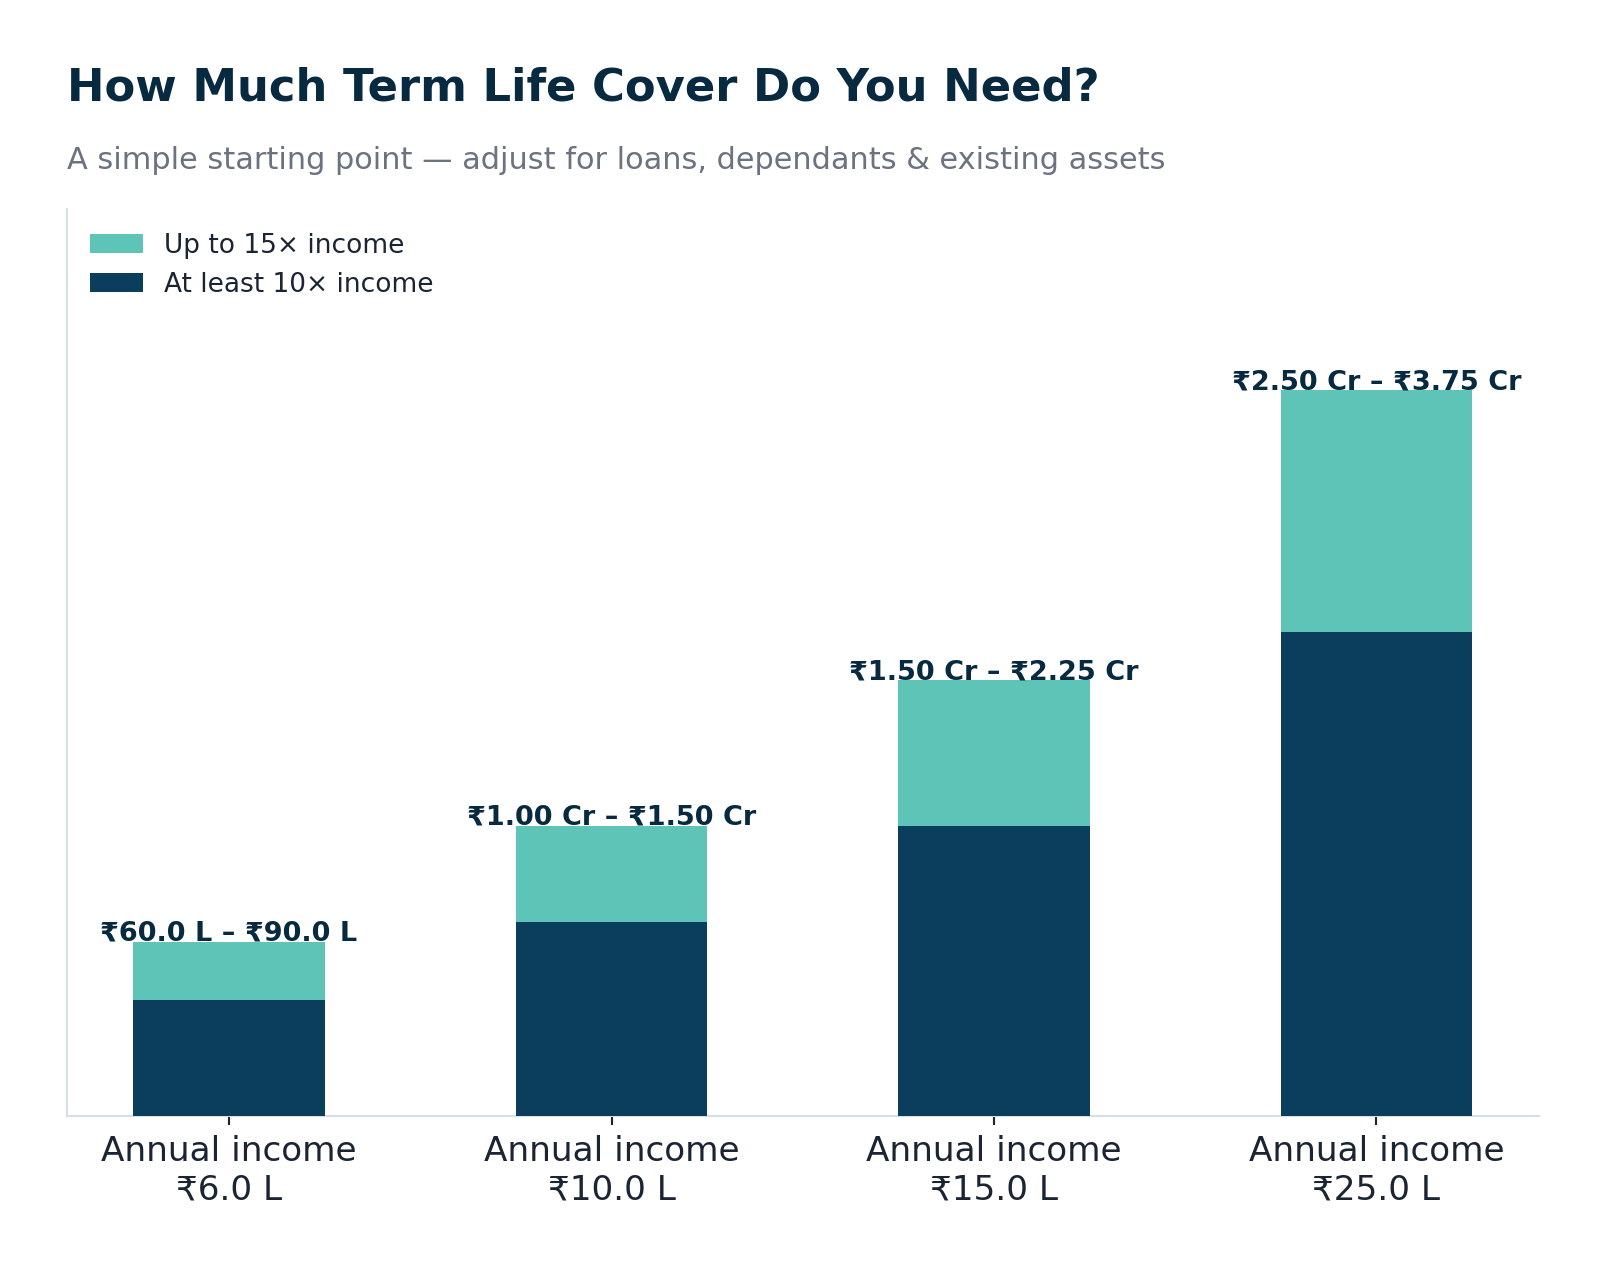
1. Life insurance (term plans). Protects your family's income if you're no longer there to earn it — for almost everyone with dependents or liabilities, this means a pure term plan sized to actual needs. See our guide on term insurance in Pune.
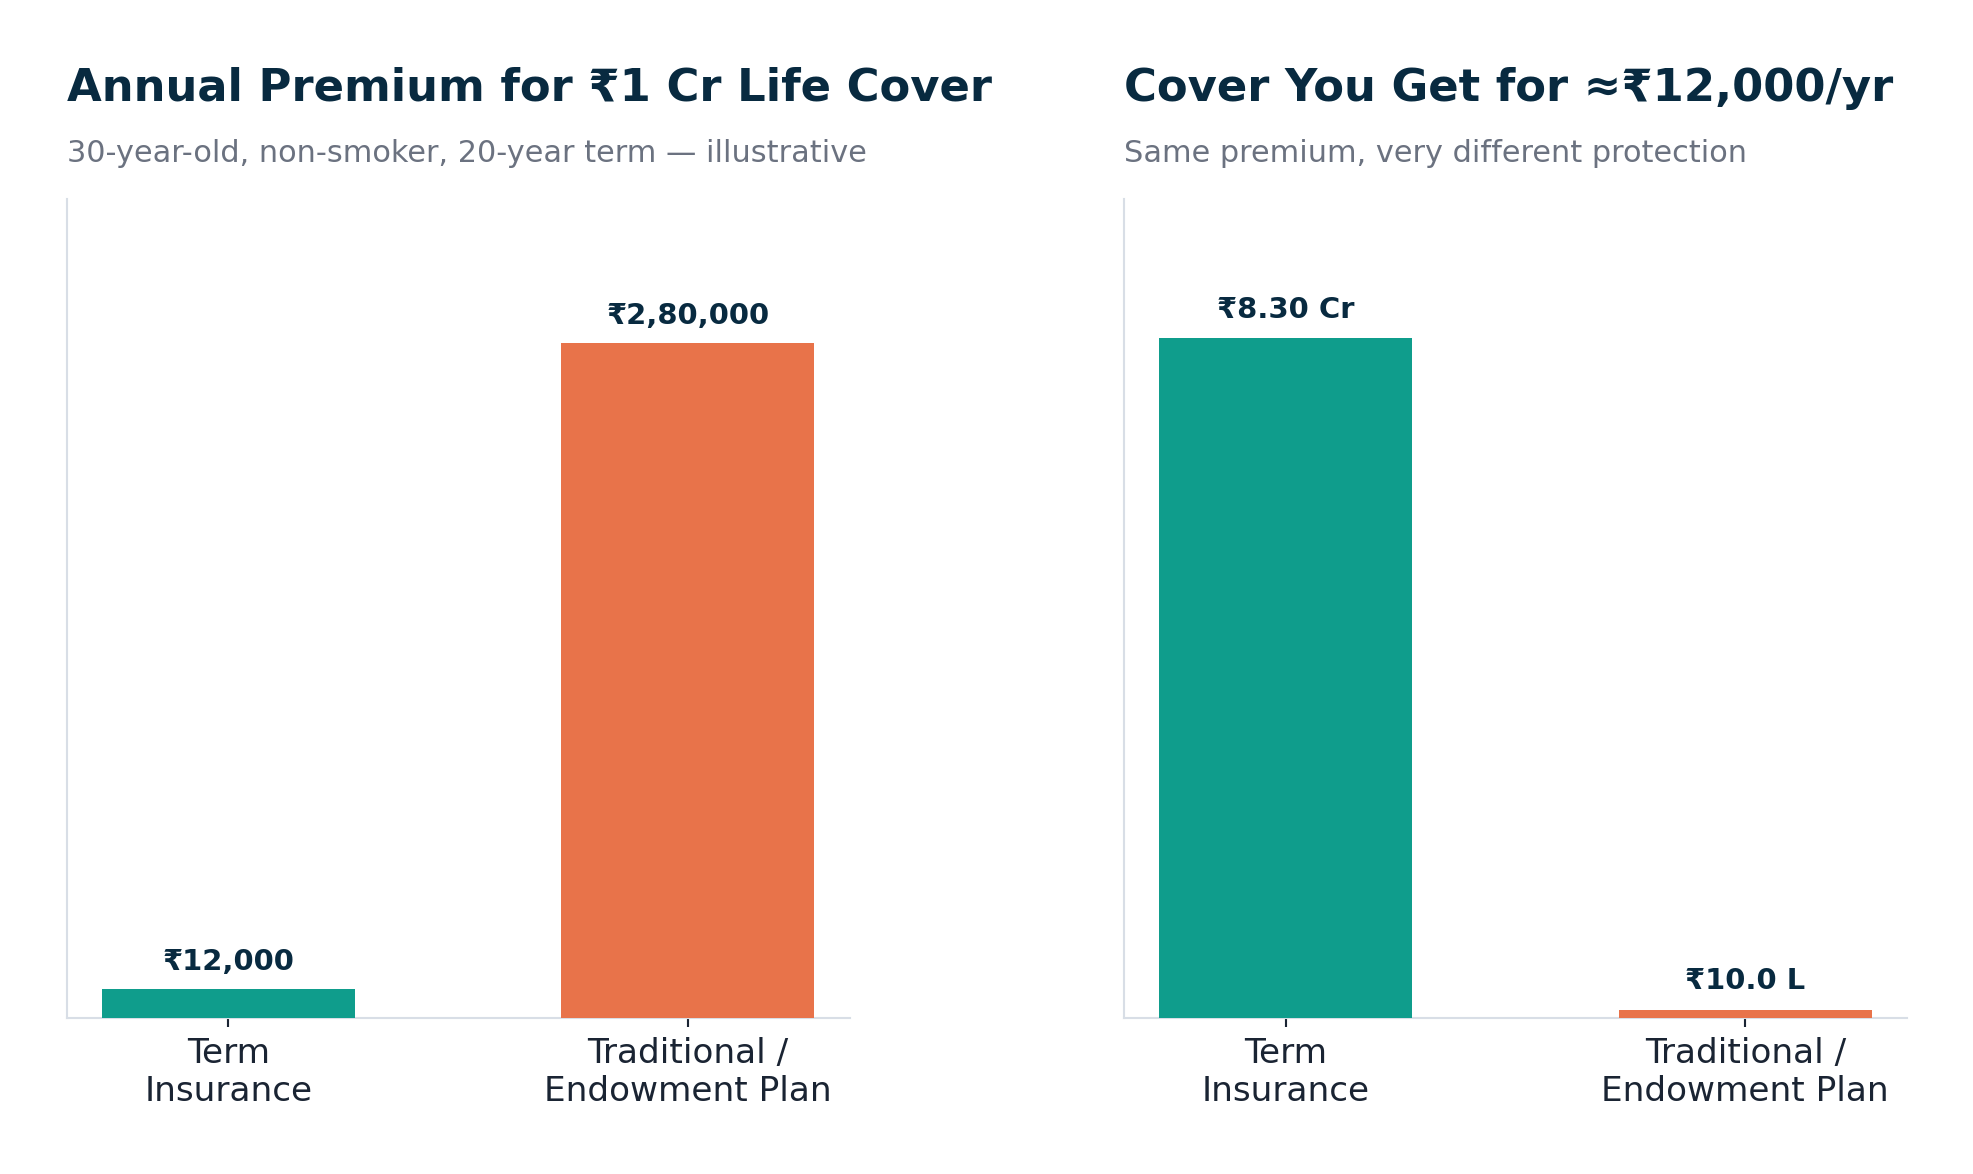
Ask most people to describe their financial plan and they'll talk about SIPs, stocks, or a PPF account. Ask about their insurance and the answer is vaguer — "I have some cover through work" or "not sure how much." As an insurance advisor working across Pune, our starting point is always the same: insurance isn't bought once and forgotten — it's the foundation that protects investments, savings and goals from being derailed by a single bad event. The Three Pillars of a Complete Insurance Plan 1. Life insurance (term plans). Protects your family's income if you're no longer there to earn it — for almost everyone with dependents or liabilities, this means a pure term plan sized to actual needs. See our guide on term insurance in Pune (/insights/term-insurance-advisor-pune) . 2. Health insurance. Protects your savings from hospitalisation and treatment costs, whether or not you have employer cover. See health insurance for individuals and families (/insights/health-insurance-advisor-in-pune) and why corporate employees still need their own policy (/insights/health-insurance-for-corporate-employees-pune) . 3. General insurance. Motor insurance (mandatory by law), home/fire insurance, and increasingly cyber and personal accident cover — often bought as a compliance formality rather than adequate protection. A Simple Framework: What Should You Insure First? Priority Insurance type Why it comes first 1 Health insurance (self + family) Highest probability of being needed; protects savings from medical shock 2 Term life insurance (if dependents/liabilities) Protects family income if the primary earner is gone 3 Motor insurance (comprehensive) Legally mandatory, genuinely likely risk 4 Personal accident / critical illness riders Fills gaps health and life insurance don't cover 5 Home/asset insurance Protects a large, often under-insured asset Investments should generally come after the first two are in reasonable shape — not before, and not never. Common Insurance Mistakes We See in Pune Households Treating employer group cover as sufficient for health (and occasionally life) — both usually end the day you leave the job. Buying a traditional/endowment or ULIP policy for "life cover" when a term plan gives far higher cover for a similar premium — see our term insurance guide (/insights/term-insurance-advisor-pune) . Under-insuring health cover to save premium, then facing a large gap at claim time due to sub-limits. Not insuring parents separately, assuming a young family's floater covers them too. Letting a policy lapse over a missed renewal, losing continuity and facing fresh underwriting. Never reviewing cover as income, family size and liabilities change. How an Insurance Advisor Adds Value Beyond a Price Comparison Website Comparison sites are useful for shortlisting premiums. An advisor matters most in three places: needs-based sizing (factoring in your actual liabilities, dependents and existing cover, not a generic multiple); policy structuring (the right riders, room-rent limits, sub-limits and network hospitals near where you live in Pune, not just the cheapest headline premium); and claims support — the moment a self-purchased online policy offers the least help, and where an advisor's value is most visible. Why Regulatory Registration Matters When Choosing an Advisor Ask any insurance advisor whether they operate under an IRDAI-registered distribution arrangement, and for investment recommendations, whether they're an AMFI-registered mutual fund distributor or SEBI-registered investment adviser. A credible advisor answers without hesitation. Money n Wealth (Predics Fintech Services Pvt Ltd) is regulated under SEBI's framework as an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered Portfolio Manager Distributor (APRN-07444), with insurance solutions under IRDAI-registered arrangements — full details in the disclosure at the end of this page. Frequently Asked Questions Do I need a separate advisor for life, health and general insurance, or one for all three? One advisor can typically handle all three, provided they hold the right registrations and take a needs-based approach rather than pushing the highest-commission product. How often should I review my insurance cover? At least once a year, and after any major life event — marriage, a child, a home loan, a significant income change, or a parent moving in. Is insurance an investment? Pure protection products (term, health) aren't investments and shouldn't be judged on "returns" — their value is the cover. Investment-linked products (ULIPs, endowment) blend the two, usually at the cost of doing either optimally. What's the first policy I should buy if I have none at all? Health insurance, followed closely by term life insurance if you have dependents or liabilities. Both are foundational; neither should wait. Want a full review of your current insurance coverage? Start with our free insurance portfolio checkup (/free-insurance-checkup) or contact our team (/contact) .